Showing posts with label nationwide insurance. Show all posts

Wednesday, October 18, 2017

The Rise of the One Car Family

one car family
For the last 40 years, two-car families have been the norm in the United States. And it hasn’t been uncommon for some families to own three or more cars
But auto-industry experts now say societal and technological changes could spell the end of the two-car family.
“Right now in the U.S., 57% of households have two or more cars,” says Gary Silberg, KPMG’s national sector lead partner for the automotive industry. “But I think we’re going to see that change. The rationale for ownership is changing. We’re getting to the point where maybe you only need one car instead of two.”
Silberg predicts that by 2040 the share of two-car families will decrease to 43% – and that percentage will continue sliding. Two major forces that are driving the change, he says: self-driving cars and the growing popularity of on-demand, ride-share services.

Counting the cost

A car has long been viewed as more than just a means of transportation in American culture. It’s often been a symbol of a person’s taste or affluence. However, for many Americans today the economics of car ownership no longer make sense, Silberg says.
“Spending approximately $30,000 for something that loses 11% of its value the minute you drive it off the lot, and then sits idle 90% of the time, isn’t the most rational economic decision,” he notes.
The realization for many, according to the Los Angeles Times, is that cars are “one of their most underutilized – but most expensive – assets.”
As new alternatives to driving appear and the use of mobile communication devices increases, owning a car is becoming less of a necessity, according to Silberg. Today, more people live in urban areas than in rural settings, which makes mass transportation and emerging alternatives more accessible.
“In urban areas, the cost of vehicle ownership tends to be much higher, and other alternatives ranging from bikes to mass transit to mobility on demand much cheaper and more convenient,” Silberg says.
If the overall cost of purchasing and owning a car seems expensive, you want to find ways to save. Affordable car insurance with many opportunities for discounts is a great place to start.

Sharing the ride

Ride-sharing services have made getting around in urban areas easier than ever. But the concept isn’t as new as we might think. In 1914 a Los Angeles-based car salesman named L.P. Draper came up with an innovative solution to the long lines of people waiting for rides on the trolleys.
Draper put a sign on his car and offered to take passengers where they needed to go for a nickel. Within a year, operations had expanded and his fleet was averaging 150,000 passengers a day in Los Angeles, 50,000 a day in Seattle and 45,000 daily in Kansas. But as cars became more accessible the company faltered, and by 1919 it had disappeared.
According to Uber CEO Travis Kalanick, that model is being resurrected through ride-sharing services that are going to continue evolving with the addition of components such as carpooling and, eventually, self-driving cars.
“With the technology in our pockets today, and a little smart regulation, we can turn every car into a shared car,” Kalanick said in a TED talk in February.

Who needs a driver?

Driverless cars, which until just three or four years ago seemed like a fantasy reserved for science fiction, are creating another ripple in the waters of change. When combined with the ride-sharing and on-demand mindset, self-driving vehicles may change the dynamics of car ownership in ways that present a wide range of opportunities for both technology and automotive companies.
The potential shift in the automotive market brought about by self-driving vehicles is something already being studied at the University of Michigan. Through an initiative involving government and auto-industry representatives, the school’s Mobility Transformation Center is working to make its home base of Ann Arbor the first city to have a fleet of networked, self-driving cars. The mobility center is creating a 30-acre test area to allow researchers to study how the cars will act in a city environment, in hopes of having the program operating in 2021.
The Michigan model could result in Ann Arbor residents not needing to own vehicles. They could use technology to summon a car when needed and the driverless vehicle would pick them up, take them to their destination and then move on to the next passenger. Larry Burns, a former General Motors research chief and a professor at the University of Michigan’s College of Engineering, says such developments would eliminate the current state of cars sitting idle and taking up parking spaces while not in use.

Kids these days

Analysts are also pointing to changes in the habits of young people entering their licensed-driving years as additional factors influencing car ownership. While earning a driver’s license and getting a car has long been a much-anticipated teenage rite of passage, many millennials say they are content with a car-free lifestyle. A study by the research firm Penn Schoen Berland found that more than half of millennials like the idea of sharing rides, and more than one-third were willing to rent out their cars.
Furthermore, a 2015 study by Frank N. Magid Associates found 18% of respondents age 18 to 64 had used a ride sharing service in 2015 – a jump from 5% in 2014 – and 22% would delay buying a new car because of the availability of such a service.
The study’s findings prompted its author, Andrew Hare, director of digital research and strategy at Magid, to paint a picture of a new landscape for the auto industry.
“Even if only a modest number of consumers begin to prioritize car-sharing over ownership, the car industry is in trouble,” he wrote.

Monday, October 16, 2017

How to Start a Small Business on a Shoestring Budget

How to Start a Small Business
Have you ever had an idea for a small business? Maybe it’s a unique product you believe would be a hit, or a brick-and-mortar storefront that would provide a needed service to a neighborhood.
For those would-be entrepreneurs who actually take steps to realize their business idea, however, many eventually hit a brick wall. Financing a business startup can often prove too big of an obstacle or present too much of a commitment in time and resources. As much as you may want to run your own small business, quitting your full-time job and mortgaging your home in order to get a business off the ground can be too much risk to take on.
But many businesses can be started on a shoestring budget without a full-time obligation. In fact, some of the best small business ideas can be found in favorite hobbies you’re already doing in your spare time. There are countless stories of entrepreneurs who turned their weekend passions into full-time, successful businesses. The key to a successful shoestring startup is to combine an activity you enjoy with an identified business niche.  It’s also wise to protect your new startup and its assets with the right business insurance, such as Nationwide’s businessowners policy (BOP), designed with the small business owner in mind.

Building a hobby into a business

Following a passion can be a key ingredient in a successful shoestring business, which is loosely defined as requiring less than $1,000 in startup costs. Such startups should not require special skills, or skills that can’t be acquired in a short time with the right resolve.
An example of a shoestring business might involve a person’s love of photography—the shutterbug who is always taking photos of family events or nature scenes. That passion could be parlayed into work in wedding photography, gaining experience by assisting an established photographer or building a portfolio by photographing friends’ or family members’ weddings for free. It’s also a business with working hours on the weekends, making it easier to manage with a full-time job.
Likewise, an avid hiker and outdoor enthusiast could turn his passion into a business by leading tours as a field guide. Or, a dedicated knitter could build a following by selling her unique patterns and designs online.

Promoting your new business

Small business owners such as these are able to keep marketing expenses on a shoestring level by promoting themselves through word-of-mouth, or by designing a website on the cheap to help drive business. Social media sites such as  Instagram and Facebook are excellent tools to attract customers and are free—other than the time needed for posting content.
Harnessing the power of social media is a great no-cost way to promote a shoestring startup, such as one inspired by a love of food and cooking. Whether you enjoy baking desserts or re-creating beloved family recipes, posting a menu and photos of your day’s offerings and taking delivery orders can be done online or through popular mobile apps with no overhead costs required. A food-centric business such as this can also gain customers at farmers markets or as a street vendor tweeting out times and locations to followers.

Protecting your new business

While money can be tight for a startup, you shouldn’t cut costs when protecting your company and yourself from the risks involved with running a business. Luckily, Nationwide offers customized insurance solutions tailored to your budget and needs. Learn more about how small business insurance can help build and protect your company, and request an online quote today.

Monday, October 9, 2017

The Lowdown on College Student Health Insurance


College students may think they’re indestructible, but like many other groups they are susceptible to injury and illness. That can make student health insurance valuable.
College students are part of a demographic that is generally very healthy, although college living often creates its own specific health-care needs. Health insurance for students can help provide coverage for these needs.
Student health coverage options
When it comes to college student health insurance, families have three options:
  1. Buying a student health plan through the college (if it is offered)
  2. Keeping the student on the parents’ plan
  3. Enrolling in the Affordable Care Act’s health insurance marketplace.
Which of these options is best for your family?

Advantages of a separate student health plan

Cost is a big consideration. A student plan is often less expensive than other types of health insurance, and it provides the care most likely to be needed by young adults. If student health insurance is billed along with tuition and fees, then it can be paid for through the student’s financial aid package.
Another consideration is access to providers. Because health insurance is generally local, the parents’ plan may not cover services in the college town. That could mean high out-of-network rates, especially for an emergency room visit. A student health plan will include local providers, alleviating that problem.
For students attending a college that does not offer a student health plan, parents may want to research services that are included in different plans offered by their employers. This is especially important if the student has conditions that require working with a local health care professional. In some cases, it may make sense for the student to purchase a plan on the insurance marketplace. The student’s physician may be able to recommend local providers, making the selection process easier.

Study abroad

Some college health insurance plans include coverage for study-abroad programs. Others offer coverage specifically for students who will be taking advantage of these opportunities.. Health coverage is a concern, but there are policies that address it.

Staying on a parent’s plan

The choice of health insurance plan for a college student isn’t a “one and done” decision. Under the Affordable Care Act, people under the age of 26 can stay on their parents’ health insurance plans in most circumstances. They are also allowed to leave their parents’ plans and return, so using student health insurance will not affect that benefit. So, if it takes new college graduates a while to find a job, they can still have access to coverage through the family plan.
If staying on a parent’s plan isn’t an option, getting an individual student health policy might be the right choice for you. Click here to find out more about college student health insurance.

Friday, October 6, 2017

Millennials and Generation Z: How to Prioritize Finances to Get Ahead

financial planning for millennials
For Millennials, figuring out how and where to save money and invest it is a little trickier than for previous generations.
In many ways this group has the same financial concerns of previous generations. They might be paying off student debt, saving for a house, putting money into retirement accounts, building an emergency fund and even saving for their kids’ schooling. While similar, though, the Millennials’ situation isn’t exactly the same as it was for previous generations.

What ages are Millennials and Generation Y?

Millennials, also known as Generation Y, were born somewhere between 1980 and 2000, the specific years depending on who’s defining it. Right behind them is Generation Z, born after 2000. This group includes anyone from a baby to a high-schooler. Some may be thinking of their future, but they’re probably aren’t doing much to plan for it. But they’ll face the same financial constraints of Generation Y.

How is financial planning different for Millennials?

Combine pension uncertainties with Millennials moving more than previous generations, as well as the prospect of their becoming entrepreneurs or freelancers rather than paid employees, and it makes sense that the retirement burden will fall on them. This, of course, adds more financial pressure than previous generations experienced.

Financial advice for Millennials

  1. Have a cash emergency fund with three to six months of living expenses. That helps with any unforeseen expenses, such as car or home issues not covered by insurance or job loss. This way an emergency doesn’t cause the person to tap into his or her retirement account, which can trigger adverse tax consequences, or to acquire high interest credit card debt. Once the emergency fund is established, it’s time to tackle other financial issues.
  2. Pay down debt. Start with consumer credit cards, as the interest rates on these are usually the highest, often around 18% to 20% ,. Managing student debt is a big concern for this generation. According to the National Financial Capability Study, about 40% of Millennials have student debt and more than a third have car loans. About 30% have more than one type of long-term debt, which might also include a mortgage. That makes debt management a big priority.
  3. Start a retirement account. Starting one in your early 20s makes it much easier to reach a retirement goal than in your 40s. Take advantage of an employer’s 401(k) match, if available. That’s free money. With additional money to invest, open a Roth IRA where the money grows tax free.
Think about this: Compound interest works even better for teenagers than for mid-20s Millennials. A $2,000 savings in a Roth IRA, at 7%, will add up to more than $65,000 by the time you’re in your 60s. Wait for 10 years to invest the $2000 and you’ll wind up with about $33,000. Get more facts on Millennials and saving for retirement with this infographic.
While for Generation Z these suggestions might seem to deal with remote issues, high school is a good time to start thinking about finances. Attitudes about money and savings are formed early.

Raise your financial consciousness

Spend an hour a week on your finances, understanding what you owe on loans and living expenses and exactly what money is coming in and going out. If there’s continually not enough money at the end of the month, consider taking a part-time job or adding freelance work into the mix.
Another option: Lower your spending. During that weekly financial time, review your retirement plans and make sure you have the proper insurance in place, such as renter’s insurance.
Though conventional wisdom says to buy a house, that’s not the right decision for everyone.  Buying a house doesn’t make sense in all situations, given the high divorce rate and Millennials moving frequently. Either contingency can make a home purchase problematic and can cause financial losses, especially if the home needs to be sold within the first few years.
When your finances are under control, take a look at your life goals, whether that means taking a big vacation to Europe, saving for an engagement ring or buying a house. Having a clear sense of priorities helps define goals and on how to get going on the path to those goals. Find a financial advisor you trust who can help get you started on the path to financial security.

Wednesday, July 26, 2017

6 Tips for Safe Online Banking

is online banking safe
More than half of U.S. adults bank online, according to Pew Research Center, and about a third of them bank via cell phone. Given the popularity, it’s important to ask; Is online banking safe?
Despite concerns about identity theft, online banking is as safe as any other banking transaction, says Murray W. Kenyon, senior vice president of technology risk management for BITS Financial Services Roundtable. However, when consumers conduct transactions online, they need to be conscious of their decisions because certain online behaviors can put them at risk, he adds.
Here are six online banking security tips to help keep your money and identity safe:

1.Change your password regularly

The best thing consumers can do to protect themselves is to change their passwords every 90 days, Kenyon says. Never use a word and always use a combination of upper and lower case letters, numbers and special characters. Words are too easy to guess, particularly if they’re related to your persona, such as your mother’s maiden name, the street where you live or your pet’s name.
The longer the password, the better, Kenyon adds. Many government agencies require passwords to be at least 14 characters. Kenyon offers this tip for creating a long password that is easy to remember: Pick a well-known verse and add numbers and letters to it that will be easy to remember. Make your password even harder to crack by replacing letters with special characters.

2. Refrain from using public computers or Wi-Fi when banking online

Anytime you are using public Wi-Fi, you have to assume that someone can access your browser history and your password. So if you are doing anything that requires you to log in, such as banking or reading email, you are putting yourself at risk, Kenyon says. This applies even if you have your email or other password-protected sites set up to automatically insert your password for you and log in.

3. Check your bank statement regularly

Check your bank statement each month, Kenyon suggests. Even though banks are highly skilled at recognizing fraud, particularly with credit cards, they might not always be able to catch every questionable transaction among every customer, so you should be sure to review your statement monthly.

4. Use licensed anti-virus software

Even Mac users need to invest in good anti-virus software, Kenyon says. Be sure to check for updates frequently. Either set your computer to check for updates automatically and alert you or plan to check yourself every Saturday or Sunday morning. But, Kenyon warns, don’t set your computer to download the update automatically. Downloading manually provides the best protection from malware and viruses.

5. Disconnect your Internet when not using it

Computers that are always connected to the Internet are vulnerable. Most consumers get their internet through their cable company and the Wi-Fi is always on. Be sure your Wi-Fi is password-protected, Kenyon states, and if you can, it’s a good idea to disconnect your computer from the Wi-Fi when you’re not using it.

6. Type your bank URL every time instead of using email links

Never click on a URL in an email, even if it looks like it’s from a trusted source, Kenyon says. “The email and link might look very legitimate but it could take you somewhere you don’t want to go,” he says. Always retype the URL into your computer before using it or bookmark your bank’s actual authenticated site, especially if you are using it for an online transaction or to provide sensitive information.
For more online banking security tips on protecting your accounts, as well as a cyber-security quiz to test your digital habits, visit Nationwide’s cyber security resource center. Nationwide Financial is a member of the Financial Services Roundtable.

Monday, July 24, 2017

How to Be a Friendly Neighbor

neighborhood etiquette
A plate of cookies can go a long way.
“Getting to know people is a peacemaking strategy,” says Laura Jeffords, an Asheville, N.C. community mediator who is on the board of the National Association for Community Mediation (NAFCM).

Starting off as a friendly neighbor

Making friendly overtures to newcomers sets the tone for your own relationship and can shape the culture of the entire neighborhood, says Jeffords, especially in changing or growing areas popular with families escaping cities, retirees seeking peace and quiet and longtime residents who expect to raise livestock or pets on their land.

Dialogue can help set neighborhood etiquette

People with different backgrounds, lifestyles and cultures often have different expectations about what it means to be a respectful, friendly neighbor, she says. Someone who wants to be left alone may not be happy to open the front door on Saturday morning and be faced with small talk from neighbors out for a walk. Conversely, newcomers seeking friends may misconstrue neighborly boundaries as standoffishness.
All of that is often unsaid, and that’s why conversations help defuse conflicts before they even start, says Jeffords. “The ultimate goal is for everyone to live peacefully in the neighborhood,” she says. A great conversation starter is to ask what the neighbor wants from living in the neighborhood. You can find mutual aspirations and bond over shared hopes.

Look over ordinances and rules

Review municipal ordinances and homeowners’ association rules to understand what’s OK before complaining. Homeowners’ associations regulations can dictate details right down to visitor parking and when it’s all right to water flowers. Municipal noise and nuisance ordinances usually outline what activities are allowed when. If your neighbor revs up the leaf blower at 8 a.m. on Saturdays, exactly when the law says he can, he’s perfectly within his rights.

How to approach a neighbor with a complaint

If a problem emerges, approach your neighbor with the expectation that you can easily work out a solution instead of expecting pushback. Jeffords says that a common problem of afternoon noise – from barking dogs, children playing outdoors or construction – can be disruptive to some.
Neighbors may not realize how disruptive the noise is for you. Explain the impact of the noise and ask how your families can arrive at a solution. Most people, are sympathetic and will offer a compromise, such as keeping a dog inside in the afternoon. After all, they’ll expect the same courtesy when they make requests of you. Common disputes, according to NAFCM records, include pets, pet noise, trash and traffic.
Jeffords’ tips for handling such disputes: Anticipate and try to mitigate the impact of traffic, congestion, parking and inconveniences if you run a home-based business that involves deliveries or a stream of clients to your house. Even regular meetings of a book club can cause difficulties if neighbors can’t easily get into their own driveways. Set rules and expectations for business operations and guests to minimize the impact on your neighbors.

Home improvement neighborhood etiquette

Home improvement projects inflict a heightened level of disruption, especially in city neighborhoods. Before your project starts, review neighborhood regulations and rules with the contractor. You might even draw up a courtesy sheet and ask the contractor to give it to all subcontractors so they know what disruptions are allowed, and when.
Clue your neighbors into the project schedule so they can plan accordingly.
Walk the project site daily and pick up debris that might end up in neighbors’ yards, especially important when they have pets or small children. When it’s all over, invite your patient neighbors over for an open house so they can see what all the fuss was about.

Find easy ways you can help your neighbors out

It’s always smart to turn your daily activities into an advantage for your neighbors. If you’re always catching the delivery van, offer to hold packages for neighbors with 9-to-5 jobs. If you’re nitpicky about your garden, offer to water your neighbors’ plants while they’re away for the weekend. If your neighbors are going to be away for an extended period, offer to look after their house. There are a few things a neighbor can do to help keep a house safe when the owners are away.
Having an open dialogue about neighborhood etiquette and offering a few friendly gestures can go a long way. That’s the kind of give-and-take that brings neighbors, and entire neighborhoods, together.

Tuesday, June 27, 2017

8 Tips for Finding a Good Contractor

how to find a contractor
Choosing the right contractor for your renovation or building project is one of the most important construction decisions you will make. A good contractor can ensure quality work and a smooth renovation, while the wrong one can trigger nightmares. Here are eight tips to help you make the right choice when hiring a contractor:

1. Have plans ready

Know exactly what you want in terms of plans and building materials before interviewing contractors. The more details you can provide, the more accurate their bid will be.

2. Get recommendations

Get recommendations from family and friends, local builders’ associations such as the National Association of the Remodeling Industry and your local Master Builders Association and from sites including Angie’s List. Although building inspectors may not give recommendations, they may tell you whether particular companies’ work generally passes initial inspections.

3. Interview candidates

Ensure candidates routinely build projects of the type and size you are proposing. Talk with three or four contractors about your project, expectations and timeframe. Learn how many projects they work on simultaneously, and get references and a list of recent projects. Also, ask how long they’ve worked with their subcontractors. Contractors should be willing to provide financial references from suppliers or banks.

4. Check licensing

Expect to see candidates’ state contractor’s license and certificate of insurance. Most states require contractors to have workers’ compensation, property damage and personal liability insurance. Check with the Better Business Bureau or your state consumer protection agency to learn whether contractors on your list have liens against them from former clients, suppliers or workers. An Internet search also may reveal valuable intelligence.

5. Visit job sites

Assess their crews’ work ethics for yourself, including how they treat others’ property. Do they minimize construction debris and dirt? Do they start work quickly or spend undue time on breaks?

6. Get bids

Have your top two or three candidates provide written bids for your project, based on the same specifications. Insist they categorize costs for materials, labor, profit and any other expenses. Common bid items are time and materials, fixed price and costs plus fixed fee. Expect materials to account for about 40% of the overall costs and profit to account for 15% to 20%. The lowest bid isn’t necessarily the best. If it’s significantly lower, that contractor may cut corners. If bids are comparable, choose the contractor with whom you best communicate.

7. Set a payment schedule

Payment plans vary according to project size. Expect to pay 10% of the estimated cost when the contract is signed and three payments of 25% evenly spaced throughout the project. The final payment should be made only after you are satisfied with the completed work.

8. Put the contract in writing

Incorporate every project detail in the contract. That includes: payment schedule, proof of liability insurance, workers’ compensation, start and finish dates, materials to be used, a lien release in case the contractor fails to pay suppliers or subcontractors and how changes will be handled.
If your top choice isn’t available, it might be a good sign. Usually the best contractors are busy, so be patient and be prepared to wait to start your project, with the right contractor.
Be sure to contact your Nationwide Insurance agent before you begin work and after your project is complete to ensure your homeowners policy will cover your project and any improvements you’ve made.

Monday, May 1, 2017

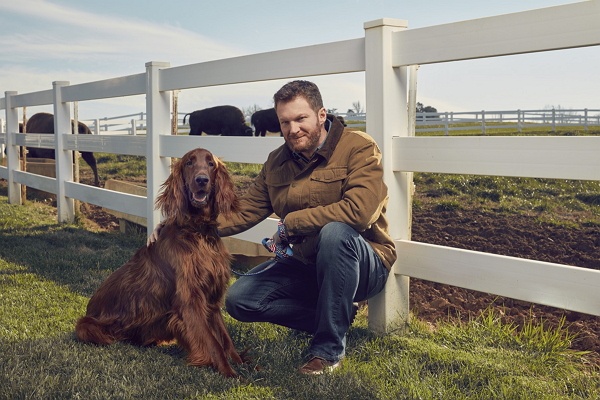
Pet Insurance Buys Peace of Mind for Dale Earnhardt Jr.

Pet Insurance Buys Peace of Mind for Dale Earnhardt Jr.

Dale Earnhardt Jr. and his dog.
As Nationwide’s current ad campaign highlights, Dale Earnhardt Jr. knows how important it is to insure and protect his “many sides” including his car, his small business, and his home. He takes that same protective approach to his beloved pets.
“Pets are great, because they’re another personality in the house,” he says. “They like to do things with you. Wherever you’re at, that’s where they want to be. I think we humans appreciate that affection and camaraderie.”
In addition to enjoying his dogs’ companionship, Earnhardt says part of his responsibility as a “pet parent” means keeping them healthy. Junebug, a Pomeranian, and Gus, an Irish Setter, are so much a part of the family that they even get to travel with him and wife Amy.
“They like to go to the beach, or anywhere there’s a lot of grass for them to run around on,” he says, adding that even when he’s traveling for work, they can find a place for the dogs to play.
“Some of the tracks we go to have fenced-in areas and dog parks nearby where they can play.”

Healthy = Happy

Maintaining good health in both dogs is a priority in the Earnhardt household. Both he and his wife, Amy, make sure that proper diet, exercise and veterinarian visits are part of the routine.
“Amy has a special food that she gets from the vet, and we take [the dogs] to the vet quite regularly, any time we notice something isn’t quite right,” he says. “They’re always around us and we play with them a lot, so we can tell when they’re not feeling well. We really try to stay on top of that.”
That’s where pet insurance can come in handy, he says, by helping defray costs of visits, treatments and, in case of a more serious disease, it can help cover the cost of surgical procedures.
“I had an 11-year-old Boxer named Killer [who got cancer] and we were hoping it was treatable, but it wasn’t,” Earnhardt recalls. “His treatment was very expensive. Having pet insurance gives me peace of mind, knowing if something like that happens, we have it covered.”
While he has loved all of the pets he has had throughout his life – everything from hamsters, cats, dogs and even a rabbit – he says that the bond he has with Gus is unlike any other he has experienced.
“My connection with him is stronger than any pet I’ve had,” he explains. “Keeping him healthy and safe is so important to me, and having pet insurance is critical to that.”
If you’re a pet owner, make sure you have a plan in place to protect your pet’s health and safety. Learn more about the benefits of pet insurance.     

Wednesday, March 1, 2017

8 Tips To Keep Your Family Safe From Heating Fires

Hey ya'll although the weather has been great lately I am sure we still have some cold Virginia days ahead.  I found this article about how to take care of your house and appliances to prevent house fires.  If you have ever known someone who has experienced a house fire, you know how terrible they can be.  Follow these easy tips to keep you family safe.  If you need to get your house insured give me a call!


Overall, heating equipment is the second leading cause of U.S. home fires and home fire deaths. There are between 350,000 and 400,000 house fires in the United States every year that result in almost $8 billion in annual damages, according to the National Fire Protection Association.

A heating fire can be catastrophic to a homeowner. Space heaters, fireplaces and water heaters are the biggest culprits but any type of heating element, including stoves and heating units, can cause fires.

Here are eight tips to keep you and your family safe from home heating fires this winter:

Inspect your furnace
Contact an HVAC professional to inspect your furnace and clean all the ducts. Remember to change your furnace filter each month during the winter and to remove all flammable material from the area around your furnace.

Clean your chimney
If you use your chimney a half-dozen times or more each year, it is a good idea to have it cleaned of soot and creosote every year. If you don’t want to hire a chimney sweep, consider a Creosote Sweeping Log, which can be bought at any home improvement store.

Check your chimney for structural damage
Make sure your chimney doesn’t have any cracks. If your chimney does have air leaks, it can change the flame in the fireplace and possibly ignite and cause a fire outside the fireplace.

Use a diffusion screen with your fireplace
A diffusion screen will prevent a flaming log from rolling out of the fireplace or sparks from popping out to cause a fire. If you have carpeting or wood flooring in front of your fireplace, it’s especially important to use a diffusion screen.

Be careful with space heaters
According to the U.S. Fire Administration, space heaters are involved in 74 percent of fire-related deaths. The best way to prevent a home fire caused by a space heater is to purchase one with an emergency cut-off so that it will automatically shut off if tipped over or accidentally knocked down. Otherwise, if it falls on the carpeting and doesn’t turn off, it could easily ignite a fire.
Never leave space heaters unattended. And make sure you place your heater on a flat, level, non-flammable surface such as ceramic tile rather than on a carpet. Don’t place space heaters near curtains, bedding or anything flammable, and make sure you are plugging the space heater into a GFI (Ground Fault Interrupter) system, so that if a malfunction does occur, the electricity will automatically turn off.

Check your water heater
As your water heater gets older, the thermostat and the heating element inside will start to deteriorate and the flame will become inconsistent. This could cause a flash fire, particularly if the water heater is in the garage where it is susceptible to wind or changes in air supply that could be caused by someone opening or closing a door.

Give your boiler a wide berth
Be careful not to put flammable items, such as boxes and newspapers, around your boiler system.

Don’t forget about the laundry room
Most homeowners don’t realize the laundry room can be a source of home fires due to the duct that connects to the back of the dryer and collects flammable lint. Homeowners should have their duct cleaned at least once a year. Your dryer doesn’t capture 100 percent of your lint and some of it ends up in the ducts, and that material is very flammable. If you have enough dryer lint built up in the duct you can have a huge fire.