Showing posts with label best insurance agent in Richmond. Show all posts

Wednesday, February 14, 2018

The Complete Wedding Planning Checklist: 43 To-Do’s Before Saying Your “I Do’s”


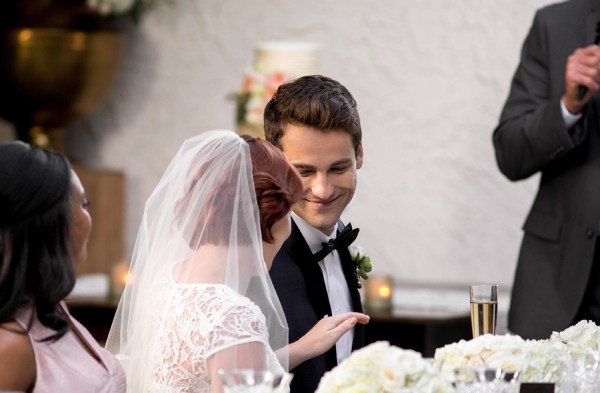
couple sitting together at a wedding


The congratulatory calls and engagement parties have waned. Now what? It’s time to get down to serious wedding planning. Fun? Yes! Overwhelming? Oh, yes. But don’t fret. We’ve compiled this pre-wedding timeline and wedding planning checklist for soon-to-be brides and grooms.

16-9 months before your wedding day

1. Create a file or binder to keep wedding information organized and together
  • Wedding planning sections should include the following:
    BudgetDate
    VenueGuests
    Wedding partyVendors
    AttireStyling
    CeremonyReception
    EntertainmentMenu
    Pre-wedding plans: rehearsal dinner, bachelor party, bridal shower etc.Post-wedding plans: honeymoon
2. Plan your budget. TheKnot.com’s budget allocation chart can help:
Reception48-50%
Attire8-10%
Flowers/Décor8-10%
Entertainment/Music8-10%
Photography/Video10-12%
Favors and Gifts2-3%
Ceremony2-3%
Stationary2-3%
Wedding Rings2-3%
Transportation2-3%
Miscellaneous8%
When planning your budget, it’s a good idea to avoid piling up bills that you’ll be paying back for years to come. Here are some wedding financing tips to help you avoid going into debt. 3. Set a date and reserve a venue for the ceremony and reception
3. Set a date and reserve a venue for the ceremony and reception
Research listings and compare features, cost, size, etc. Arrange visits and bring a list of questions to ask venue planners. Also, consider wedding insurance for protection in case of a cancellation or damage to the venue.
4. Create the guest list
  • Draft the list based on your budget and venue size.
  • Use Google Docs or similar resources to keep the list organized and easily editable.
  • Make sure guests’ names are on the RSVP card to avoid any confusion.
5. Choose your wedding party
6. Hire a wedding planner to help with details
7. Have the engagement ring appraised
You will most likely be able to have your ring appraised for free at the jewelry store where the ring was purchased. In the event your ring is lost or damaged, it’s a good idea to keep the appraisal and receipts in a safe place.
8. Insure the engagement ring for protection
Research your options when it comes to insuring your ring. You can contact your agent for more details on the steps you should take.
9. Choose an officiant for the ceremony

8 months before your wedding day

 10. Select a photographer and videographer
  • Decide on a photography style – candid, classic, edgy?
  • Read client reviews.
  • Interview prospective photographers and view their work.
  • Compare photo packages.
  • Inquire about your rights to the photos, since many photographers own the rights to all wedding images.
  • Find out post-production details, such as how long it takes to get your photos, how many you’ll receive, and whether the photographer offers retouching options.
11. Decide on entertainment
When choosing between a band or DJ, consider the following:
  • Vibe – Music sets the tone, theme and ambiance of your wedding
  • Variety – Make sure the entertainment can play the mix of genres you desire
  • Budget – While a DJ generally costs less than a band, the price of a band often depends on the number of musicians
  • Space – Check with the venue about restrictions. For example, is there a limit to the number of musicians or pieces of equipment you can bring in?
12. Choose a caterer
Schedule a tasting of what you want to serve and find out exactly what’s included, such as plates, silverware, table linens, etc.
13. Plan attire for the bride, groom, bridesmaids, groomsmen, flower girl and ring bearer
Schedule fittings and keep track of dates. Don’t forget jewelry, bag, shoes, bridal veil and other accessories.
14. Reserve a block of hotel rooms for out-of-town guests
15. Register for gifts with at least three retailers
Print out a wedding registry checklist to avoid missing any essentials.
16. Look into coverage options for any new gifts you receive
Check your homeowners or renters policy to find out if new gifts are already covered. If not, look into different property insurance options that could insure your new items.

7-6 months before your wedding day

17. Design invitations
  • Choose text and colors that are legible.
  • Order at least 25 extra invitations in the event of re-sends.
18. Plan your honeymoon
Planning your honeymoon well in advance can help avoid any last minute problems and can save you money. It’s also a good idea to get travel insurance so you’re protected if an incident affects your trip.
19. Send save-the-date cards
20. Reserve things like portable restrooms and outdoor lighting if needed
21. Book a florist
22. Create a music playlist, including a list of no-play songs
23. Arrange transportation for guests
  • Book transportation for the wedding party, as well as for you if you plan to arrive separately.
  • Hire a shuttle or bus to take guests to and from the hotel.

5-4 months before your wedding day

24. Finalize the menu
25. Choose a wedding cake
Schedule a tasting with bakeries so you can try different types of cakes, ask questions and review the bakery’s portfolio.
26. Address wedding invitations
Consider hiring a calligrapher to make your invitations more elegant and consistent.

3 months before your wedding day

27. Map out the ceremony with your officiant
28. Choose wedding favors for your guests
29. Create a list of who will be toasting at the reception
Be sure to allot time for speeches in your day-of schedule.
30. Purchase bride and groom wedding bands

2 months before your wedding day

31. Confirm times with all vendors
Send your day-of schedule to vendors and confirm appointments for hair and makeup.
32. Buy gifts for your wedding party
33. Send invitations

1 month before your wedding day

34. Get your marriage license
35. Separate RSVPs as you receive them by “attending” and “not attending”
The RSVP date should be 2-3 three weeks before your wedding in order to give the caterer a head count and set your seating chart a week ahead of time.
36. Schedule the timing for all day-of activities, such as the cake cutting and the first dance
A wedding planner or coordinator can help.
37. Put together gift bags for out-of-town guests

Week of the wedding

38. Assign seating for the reception
Create a seating chart at least a week before the big day. A site like seatingarrangement.com can help with the task.
39. Confirm honeymoon details
40. Deliver gift bags to guests at the hotel
41. Put tips and final payments for vendors into separate envelopes
42. Pack for your honeymoon
Check out our tips for efficient packing, and our guide to following TSA carry-on rules so your honeymoon isn’t derailed at the airport.
43. Breathe and enjoy as all your planning comes together!

Friday, February 9, 2018

10 Medicine Cabinet Essentials

well-stocked medicine cabinet

When it comes to first aid in the home, be prepared with a well-stocked medicine cabinet. If you need to treat an illness or injury, you will have all the basics on hand to help yourself or others.
Before you head to the drugstore, take an inventory of your medicine cabinet and what’s currently on your shelves. This is a good opportunity to clear your medicine cabinet of old prescriptions and expired products. Make this a habit and try to do this every three months. Find a local center near you that can properly dispose of old medication. Some grocery stores or community centers offer this service annually. By doing this, you won’t have to worry about how long that bottle of pink liquid has been sitting on your shelf the next time you have a sudden stomach ache.
Remember: Always follow dosage instructions as indicated on medication packaging.

Medications and first aid supplies to have on hand at all times

The following medicine cabinet supplies can treat a range of illnesses and minor injuries, from allergies and stomach aches to cut, bruises, aches and pains.
1. Emergency instructions
Tape a list of important phone numbers (doctors, Poison Control), medication instructions and allergy alerts inside the cabinet door.

2. Acetaminophen and an NSAID

Acetaminophen is a pain reliever and fever reducer. Non-steroidal anti-inflammatory drugs (NSAIDs) can reduce inflammation related to conditions like backaches and toothaches. Be aware of NSAID sensitivity in your family, especially in young children.

3. Aspirin

Aspirin works as a pain reliever for adults, but it’s also important to have on hand in case of emergencies. According to the American Heart Association, taking aspirin also helps during a heart attack. In fact, people having a heart attack are often given an aspirin by emergency medical services. However, it’s wise to be aware of aspirin sensitivity in your family, and it should never be given to children under 18.

4. Antihistamine

Antihistamines treat hives, itching and allergic reactions from a wide range of causes. Stock both oral antihistamines (the liquid or pill form that may be helpful during a serious allergic reaction) and hydrocortisone cream.

5. Decongestant, cough suppressant and flu relief medicine

You won’t want to leave home to go to the drugstore when you’re feeling lousy, so keep cold and flu relief medication on hand.

6. Antacids

If you are suffering from heartburn, these are your best bet for quick relief.

7. Antibiotic ointment

Apply this after you’ve washed cuts and scrapes with warm water and soap, then cover the wound with clean bandages.

8. Bandages

Stock up on adhesive bandages of all sizes, plus plenty of gauze and sterile tape.

9. Thermometer

Feeling someone’s forehead may be a good first step, but a thermometer is necessary for an accurate temperature reading.

10. Heat and ice packs

Keep several of these on hand, as they can provide relief for everything from headaches and sprains to injuries and sore muscles.
Staying healthy and safe is everyone’s concern. But if someone gets injured on your property, you’ll need more protection than what’s available in your emergency medicine cabinet. Make sure you’re covered with personal umbrella liabilitycoverage from Nationwide, which may help protect you beyond your homeowners insurance coverage limits.

Wednesday, February 7, 2018

How Much Does Pet Insurance Cost?

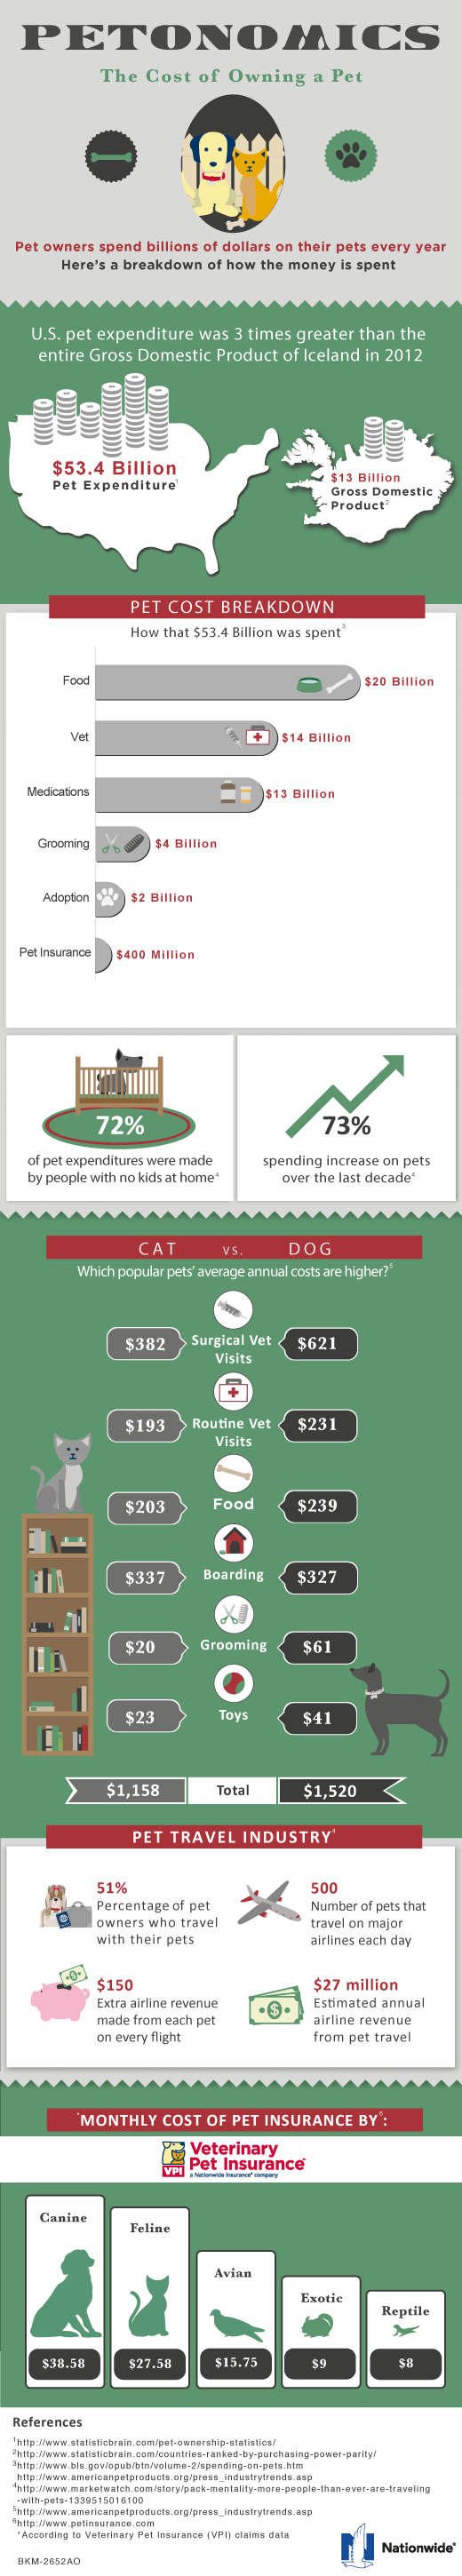
The average dog owner spends $852 annually on routine and surgical visits to the vet. Insuring your pet can help ease the financial burden. The cost of pet insurance is not only affordable, it can also help you save on pet care through reimbursements. With Veterinary Pet Insurance (VPI), monthly insurance plans might be less than you think:

Average monthly cost of pet insurance

  • Dog Insurance Cost: $38.58
  • Cat Insurance Cost: $27.58
  • Bird Insurance Cost: $ 15.75
  • Exotic Pet Insurance Cost: $9
  • Reptile Insurance Cost: $8
Compared to the monthly price of your pet’s food, the cost of pet insurance is a small price to pay for your animal’s protection.
How Much Does Pet Insurance Cost? [Infographic]

Monday, February 5, 2018

The Benefits of Minimalist Living

Living a minimalist lifestyle with smaller rooms
Accumulating things is just part of life. There are the items we need, and then there are those we don’t really need — but how much is too much? At a certain point, you may feel overwhelmed or crowded by all of your stuff. Your things may cease to have meaning, or worse, you may not be able to locate important items.
If this sounds right, it might be time to adopt a minimalist lifestyle. From a practical standpoint, relinquishing objects can help you de-clutter your living space. It also may have symbolic value, signaling a change in your perspective and priorities in life.

1. Create a minimalist living plan

You’ll have to prioritize the objects you can’t live without and those that are less important. Every room in the house can accumulate clutter. Don’t ignore any opportunity. Remember that you want fewer items.
One great way to get started with a minimalist lifestyle is to formulate a plan to systematically go through your things and determine what you want to keep. It can feel overwhelming to think you need to tackle everything in one day – and you don’t need to. Instead, break each part of the process into steps.
One idea is to set a goal of going through one room a day – or a weekend for larger rooms with more items, like your kitchen. Or, if you have a bunch of boxes to go through, sort one every evening after you get home from work. It can also help to set up a staging area somewhere else in your home; seeing the items outside their “natural habitat” makes it easier to think about their utility. However you declutter, choose the pace that works for you, and remember it’s not a race. It took time to accumulate things, and it can take some time to declutter, too.

2. Artwork and decorative objects

Artwork and ornamental objects can create a richer environment, but they’re not a necessity and can easily clutter a room. They may serve as a good starting point in your minimalist efforts. Keep only what has nostalgic value or that’s meaningful and attractive, and sell or give away the rest. If an art piece is valuable enough, consider donating it to charity.

3. Living with less furniture

Many houses have extra furniture on hand, which can overcrowd the space. Think about taking out pieces, starting with the ones that you simply don’t like anymore or that aren’t essential for your convenience or comfort. If you don’t use it frequently or have a need for it, don’t hesitate to get rid of it. Remember that some charitable services and thrift stores will pick up bulky items you want to donate.

4. Kitchen equipment and utensils

Culinary-minded households acquire kitchen gadgets and utensils quickly. You might like the aesthetics of certain items or want to purchase the latest devices. But too many small appliances and tools, like food processors and blenders, can monopolize your counter and cabinet space. So can those utensils you have doubles or even triples of — there are only so many spatulas, serving spoons or pots that you need.
Look for kitchen items you’re not using frequently or that you have multiples of. If you do an effective job of streamlining your kitchen, you’ll find that this room is easier and more enjoyable to use. This is also a helpful way to prepare for a remodel.

5. Clearing out clothing

It’s not unusual to see bedroom closets and dressers overflowing with clothes. Many of us own extra clothing, and many of us also don’t wear a good portion of our wardrobes. If you’re overstocked, pinpoint the items that you wear most frequently and donate the rest.
With these helpful ideas in mind, it’s easier to begin the de-cluttering process on your path to a more minimalist lifestyle. Whether you’re preparing for a move, cleaning the kids’ rooms after they’ve left for college or looking into adopting minimalist living, a decluttered living space provides contentment and relaxation.
Looking to enjoy even more peace of mind at home? Nationwide’s homeowners insurance coverage can help protect your important belongings, regardless of how minimalist your lifestyle is.

Friday, January 26, 2018

7 Ways to Teach Kids How to Save Money


Starting early can make a world of difference when it comes to teaching children to save and make sound financial decisions.
Luckily, there are simple ways to teach kids about money and help youngsters learn smart saving techniques. Here are some approaches to teaching children the valuable art of saving.

1. Teach kids about money with actual money 

In a world where anything can be purchased with the swipe of a card or typing of a password, the simple reality of cash can help teach the value of a dollar. That’s why using physical currency can be a smart way to teach kids about money. Counting coins and bills can also help preschoolers with hand-eye coordination and math skills.

2. Give an allowance

Giving children their own money is a good way to start teaching them how to save. Kindergarten is a great age to start a weekly or monthly allowance. A good rule of thumb is to pay $1 for every year of their age, so the incentive grows as they do. Make sure the allowance is based on completed chores, though. That way, kids understand that money is earned.

3. See the savings

Using a clear container as a bank can help give kids a sense of accomplishment watching the coins and dollars stack up. Make goals visible by marking a line on the side of the container as a target to reach. Not only does this teach children about saving, it makes reaching goals exciting and fun!

4. Teach children to allocate their savings

To introduce money management, as well as delayed gratification and charity, encourage your child to divide their money into three piles: savings, spending and sharing. You can do this online with the website Threejars.com, where kids can track their earned allowance and even earn interest on savings.

5. Set saving goals

Help your child develop savings targets to make sure savings isn’t an open-ended concept. The first goals should be reachable, fun and defined by both the parent and child. Sure, it may seem silly to save for a small toy, but the sense of achievement is worth it.

6. Teach kids about saving money in a bank account

As your child matures and has accumulated at least $100 in long-term savings, look into a bank savings account. Most major banks offer children’s savings accounts that can be opened online or at a local branch. A trip to the bank may be a new and fascinating experience for your child, inspiring a sense of maturity and financial responsibility. It’s also a great time to teach kids about other money concepts, like interest and risk.

7. Have conversations about saving

The best tool for money management is conversation. Parents should talk to their kids about money matters like budgeting and investing. Aim to mirror good money behaviors, but remember it’s also okay to admit to your own money mistakes.
Show your kids what smart money management is. Visit Nationwide Bank for information on banking, investing and more.

Wednesday, January 24, 2018

How to Negotiate Your Rent

woman negotiating her rent with landlord

Whether you’re apartment hunting and the perfect place is slightly out of your price range, or your landlord is raising the rent on your current apartment, you have the option to try and negotiate your rent. It sounds intimidating, but with a little strategy, you just might win over the landlord. Here are some ways you can go about negotiating your rent price:

Ask the landlord if rent price is open to discussion

Politely ask if the landlord is willing to discuss rent prices and when a good time to talk would be. If you’re negotiating price for a new place, it’s important to know who you are talking to. A large property company is less likely to negotiate terms, while an independent landlord has more leeway to change prices.
If you’re facing a rent increase, start the conversation at least a month before your lease ends so your landlord has enough time to consider your offer or, if need be, you have time to make other plans.

Highlight your strengths as a tenant

If you’re looking for a new place, you can show you’re financially stable by offering the landlord a few concessions, such as paying a few months of rent in advance or signing on for a longer lease which saves the landlord money in turnover.
In the case of a rent increase, you should remind the landlord what a reliable, responsible tenant you’ve been. If you’ve always paid your rent on time, are courteous to other tenants and have kept the property in good shape, make sure your landlord knows it. It can help prove your worthiness and give them an incentive to keep your current rent.

Inquire about extending the lease

Showing that you plan to stay in your apartment for a substantial length of time can demonstrate that you’re a stable investment. If the lease is annual, offer to extend it to 18-24 months in exchange for keeping your current rent. If the landlord knows he or she won’t have to take a risk with a new tenant, this could be a good compromise.

Offer to end the lease in the summer

Landlords know the summer is usually an easier time to find tenants. Since most people have more flexible schedules then, such as recently graduated college students looking for first apartments, there are simply more people looking for rental spaces. Offering to end your lease in the summer can be an attractive option for a landlord, and they might be willing to shave prices in exchange for the convenient end date.

Research the property’s value

Consider if the is rent beyond the actual worth of the prevailing market. Research rent rates by talking to other landlords or neighbors in the area. Knowing average property prices and frequency of rent hikes in the neighborhood may give you leverage.

Be open to compromise

Unless you’re simply unwilling or unable to afford the rent rate, suggest a compromise amount that you can afford. For instance, if the rent is $100 higher than you’d like, offer to pay $50 instead. Back up your offer by mentioning your research findings and focusing on your stability as a tenant.

Negotiate in person, follow up in writing

Try to talk to the landlord in person as face to face negotiation is usually best. Remain calm, polite and professional during the discussion – never rude or defensive. Follow up the discussion within 24 hours with a brief email thanking them for the meeting and reiterating your “ask.”

Have a backup plan

If you’re looking for a new place, you should have more than one apartment, house or condo on your radar. Banking on a landlord decreasing rent prices can be risky, especially if you have a set date you need to move out of your old place.
If you’re facing a rent increase, you have to decide if you’d be willing to pay the higher rate just in case negotiations don’t go as planned. If you are definitely unwilling or unable to accept the new rate, it’s a good idea to start researching new apartments. If you decide to stay and pay more each month, you can request property upgrades to make the increase more palatable, such as repainting the walls or updating the landscaping.

Rent increases aren’t the only unexpected thing that can happen to renters. Find out how Nationwide renters insurance can protect you against theft, damage to personal belongings, and more.

Thursday, January 18, 2018

5 Ways to Get Your Car Out of the Snow

car stuck in snow
Getting stuck in the middle of a big pile of snow or on a stretch of ice can be an all-too-common occurrence during the cold winter months. Luckily, we have a few tips and tricks that can get your car free in no time, even if you don’t have one of the best vehicles for winter driving. Here are some things you can try if your car is stuck in snow:

1. Clear a path around your tires

Try to dig snow and ice away from the drive tires. You want to free up a few feet in front of and behind the tires so you can move the car back and forth. Also, dig out any snow under the front or middle of your car that is higher than its ground clearance.
Of course a shovel makes this much easier, so try and store one in your trunk along with some other winter emergency items if you plan on driving in snowy conditions.

2. Rock your car free of the snow

Carefully switching from drive to reverse can help dislodge some of the snow around your wheels. “You go into drive, then reverse, then repeat,” says Mark Osborne, who oversees Michigan Technological University’s Winter Driving School. “But you have to be careful not to wreck your transmission. I put my foot on the brake at the peak of each ‘rock,’ so the car is motionless when I change gears. It’s also helpful to shift to neutral for a second before making the transition.”

3. Don’t floor the gas

You’ll always be tempted to floor it if you’re stuck. But don’t. Go easy on the pedal to give the vehicle just a little gas for a moment, then let off. Repeat to enhance the needed “rocking” motion. It’s momentum that sets you free, not power.

4. Improve traction

If you still can’t get your car free, you can next try and improve traction under your wheels. Things such as sandbags, salt, dirt or even kitty litter can be used when your car is stuck in snow. Throw several handfuls under your tires for improved traction, then try the gas again.

5. Get others to help push your car

If you have other people in your car, or friendly onlookers who can help, simply pushing your car out of the snow can be an easy solution. Gently press the gas while the car is being pushed to add additional momentum. Safety always comes first, so make sure you’re in forward gear and the ground isn’t too slippery for helpers to push.

Always keep a cool head

Whether you’re stuck in snow or hit a stretch of ice, try and remain calm. Don’t do anything abrupt, like slamming the brakes. “If you do that, you’ll transfer your vehicle’s weight to your front wheels,” Osborne says. “That lightens up the rear, making it likely that your rear end will spin.” Instead, Osborne says, gradually let off the gas and hold the steering steady until you’ve cleared the ice.
If all else fails, an emergency roadside assistance service can give your car a tow. Learn more about the benefits of our Roadside Assistance program here.
Your car getting stuck isn’t the only concern when winter comes along. Snowy and icy pavement can lead to accidents. To help you navigate inclement weather this winter, check out our safety tips for driving in a snowstorm.

Wednesday, August 16, 2017

Protect Your Home-Based Business with the Right Insurance

home business insurance
More than half of all U.S. businesses – 52% – are based in the home, according to the U.S. Census Bureau. A recent study commissioned by the Independent Insurance Agents & Brokers of America found that nearly 60% of home-based businesses do not have insurance coverage.
“When asked about the lack of insurance, nearly 40% of home-based business owners say they thought they were protected by some other type of coverage, while almost 30% say their businesses are too small to insure,” the IIABA said. “Notably, nearly 20% could not give a reason for not having insurance.”
Homeowners insurance covers incidents such as loss or theft of personal property. But if a delivery person slips and falls on your property or your business equipment is destroyed in a fire, homeowners insurance won’t protect you. Without coverage specifically designed for your home business, you put your livelihood, and possibly that of your employees, at risk. That’s why home-based business insurance is a good idea.

Choosing the right policy

No matter how small your home-based business, make sure you’re protected with the right coverage. There are three main property and liability options for home-based business insurance:
  • Homeowners policy endorsements: Adding an endorsement, also known as a rider, to your existing homeowners policy is often the simplest and most affordable way to insure smaller home businesses that don’t manufacture products on the premises or use a lot of equipment. Endorsements are also a good fit for solo entrepreneurs with few business-related visitors.
  • In-home business policy: Combining home and business insurance into a single plan, this type of policy offers more specific types of coverage. This policy is a step up from a basic homeowners policy endorsement, offering a greater range of coverage for a growing business. If your in-home business has developed into a mid-level operation with more visitors, equipment and output, this may be the policy for you. Such a policy may include more extensive property and liability coverage than endorsements, as well as business interruption coverage, which protects your income in the event your business is disrupted because of a disaster.
    Examples of what kinds of businesses would use this policy include a small baking operation that meets with clients in person and also does all baking, orders and shipping in-house; a clothing designer who fits clients, as well as manufactures and ships goods, from home or an accountant who makes regular in-person appointments and uses certain rooms in the house as dedicated office space.
  • Business owners policy: Often referred to as a BOP, this type of policy is the most comprehensive form of coverage for home-based businesses. It offers protection for claims brought by contractors, customers and employees, making it a good option for larger home-based businesses. It’s also the best fit for in-home businesses that operate in multiple locations or require extensive travel off-site.

Additional coverage

Whichever policy you consider best for the size and type of your business, be aware that you may need additional coverage not included in a standard plan. Here are some additional coverage options you may want to discuss with your insurance agent, if the plan you’re considering doesn’t include them:
  • Data compromise coverage: Helps protect you and your business from legal action stemming from a security breach that compromises confidential customer or client information.
  • Employment practices coverage: Protects against claims brought against you and your business by your employees.
  • Key person insurance: Basically life insurance on a person critical to the success of a business such as the owner, founder or a key employee, without whom the company might fail.
Most states require home-based businesses to purchase workers’ compensation insurance for employees, but purchasing this coverage is a smart move even if not mandated by law.
As you can see, in-home business insurance isn’t a one-size-fits-all consideration. Talk to a Nationwide agent about the best coverage for your home-based business.

Monday, May 22, 2017

Condo vs. Townhouse: What’s the Difference?

Condo vs. townhouse
If you’re thinking of buying a townhouse or condominium, there are some important differences between the two that you should know about. To help you decide between a condo or townhouse, we’ve provided definitions and put together a comprehensive comparison to help you make an informed decision, before you buy.
Let’s start with condo and townhouse definitions.

What is a condominium?

A condominium, or condo, is a building or community of buildings in which units are owned by individuals, rather than a landlord.

What is a townhome?

A townhome is defined as conjoined units that are owned by individual tenants. They are architecturally similar to row houses in that owners usually share at least one or more walls.
Now that we have the definitions of townhomes and condos, let’s look at some of the factors you should consider when picking between the two. Below is a side by side comparison of townhouses and condos to help you make an informed decision.
Townhouse vs. Condo
Condo Townhome
OwnershipCondo owners only own the interior of their unit. All other areas, including the building exterior, lawn and communal areas, are property of the Homeowners Association (HOA).In most townhome communities, owners own their unit’s interior and exterior, including the roof, lawn and driveway, but not the communal areas.

ArchitectureCondos come in many different styles. They may be part of a large high rise, a cul-de-sac of cottages or anything in between.Townhomes are designed in rows, so tenants usually share at least one wall. It’s common for townhomes to have two or more stories.

CommunityCondominiums often have a community focus with a club house, pool, golf course and/or similar amenity.

Some townhouse communities offer the same types of amenities as condos, but others are more private.

Homeowners Association FeesHOA fees for condos are typically higher than townhouses because they pay for exterior upkeep, such as lawn care, trash removal and pest control.

Townhouse owners pay lower monthly HOA fees because they pay for much of their own upkeep. Certain types of maintenance and trash removal are still handled by the HOA.
Home Insurance RatesHome insurance rates are usually lower for condos because owners have to insure only the interior of their unit.

Townhouses may have higher home insurance rates, since most owners need insurance that covers both the exterior and interior.

SizeAlthough condos come in many sizes and styles, they are generally smaller than townhomes.

Townhomes can be quite large and often feature multiple stories.

Maintenance FeesCondo owners often pay higher monthly maintenance fees, which go toward exterior and community space repairs.As with HOA fees, townhome owners typically have lower monthly maintenance fees, but pay more out of pocket for exterior and interior care.

PrivacyDepending on the style, condos could be private, individual homes or apartment-style units.

Townhomes share one to two walls with neighboring units, but don’t have units above or below them.

If you’re also considering co-ops, take our Condo vs. Co-op quiz and see which is right for you. And when it comes to deciding on location, take a look at our latest health of housing markets report to find out which U.S. metro areas are healthiest.
And remember, whether you choose a condo or a townhouse, Nationwide has you covered. Learn more about insurance options for condos and townhomes today.