Showing posts with label best insurance agent richmond. Show all posts

Friday, February 16, 2018

4 Easy Tips to Declutter Your House

declutter your home

Are you looking to declutter your life? The best place to start is with your home.
Piles of stuff can make you feel boxed in, and purging your house of unnecessary objects can improve your outlook and make it easier to enjoy spending time around the house, whether you just a neater space or are in the process of downsizing. But decluttering a home can feel daunting unless you have a plan.
You may want to tackle small tasks first, build a sense of accomplishment and then move on to bigger projects. You may even want to set several goals. Whatever you decide, here are four ways to get started on decluttering.

1. Use a four-bin system

To start eliminating clutter, go through your home room by room with four bins: keep, toss, donate and store. In the “keep” bin you’ll put items you want to keep but need to put in a new place. The “toss” bin goes to the garbage, the “donate” bin receives items other people can use and the “store” bin is for those things that you don’t use frequently but want to keep.

2. Clear flat surfaces in the kitchen

Clear off flat surfaces in your kitchen, including your countertops, tables and more obscure spots like the top of your refrigerator and microwave.
You’ll want to remove everything that you don’t use on a daily basis. File the pile of bills and other papers. Consider placing a toaster you use once a month in a cupboard and paring down the dozen cookbooks you’ve been keeping on top of the refrigerator to just your favorites.

3. Declutter bedroom closets

Bedroom closets tend to be a catchall. Many people toss what they don’t need or don’t have time to hang up into their closets. Take some time to organize and determine what you no longer wear or use.
One possible strategy: Remove everything from your closet shelves, wipe them down and then make decisions about what to do with various objects before you start replacing things.
If you haven’t worn something in your closet for a year or more, consider placing it in the Donate bin. Be decisive, but don’t be afraid to hang on to a few key sentimental pieces if they mean a lot to you, either.
4. Free the entryway
When you first walk into your home, do you trip on a pile of shoes? Are dozens of coats piled on a table? If your entryway is cluttered, it makes your house feel unkempt. Coat and shoe racks can solve this problem. You might also make a rule to limit shoes and coats to those needed for a season, the rest can be stored away too.
If you’re decluttering in a hurry, be sure to check out these quick house cleaning tips.
When your home is decluttered, it’s even easier to enjoy spending time in this peaceful, relaxing space. Find a homeowners insurance policy that’s tailored to your unique needs to increase your peace of mind even further.

Wednesday, February 14, 2018

The Complete Wedding Planning Checklist: 43 To-Do’s Before Saying Your “I Do’s”


couple sitting together at a wedding


The congratulatory calls and engagement parties have waned. Now what? It’s time to get down to serious wedding planning. Fun? Yes! Overwhelming? Oh, yes. But don’t fret. We’ve compiled this pre-wedding timeline and wedding planning checklist for soon-to-be brides and grooms.

16-9 months before your wedding day

1. Create a file or binder to keep wedding information organized and together
  • Wedding planning sections should include the following:
    BudgetDate
    VenueGuests
    Wedding partyVendors
    AttireStyling
    CeremonyReception
    EntertainmentMenu
    Pre-wedding plans: rehearsal dinner, bachelor party, bridal shower etc.Post-wedding plans: honeymoon
2. Plan your budget. TheKnot.com’s budget allocation chart can help:
Reception48-50%
Attire8-10%
Flowers/Décor8-10%
Entertainment/Music8-10%
Photography/Video10-12%
Favors and Gifts2-3%
Ceremony2-3%
Stationary2-3%
Wedding Rings2-3%
Transportation2-3%
Miscellaneous8%
When planning your budget, it’s a good idea to avoid piling up bills that you’ll be paying back for years to come. Here are some wedding financing tips to help you avoid going into debt. 3. Set a date and reserve a venue for the ceremony and reception
3. Set a date and reserve a venue for the ceremony and reception
Research listings and compare features, cost, size, etc. Arrange visits and bring a list of questions to ask venue planners. Also, consider wedding insurance for protection in case of a cancellation or damage to the venue.
4. Create the guest list
  • Draft the list based on your budget and venue size.
  • Use Google Docs or similar resources to keep the list organized and easily editable.
  • Make sure guests’ names are on the RSVP card to avoid any confusion.
5. Choose your wedding party
6. Hire a wedding planner to help with details
7. Have the engagement ring appraised
You will most likely be able to have your ring appraised for free at the jewelry store where the ring was purchased. In the event your ring is lost or damaged, it’s a good idea to keep the appraisal and receipts in a safe place.
8. Insure the engagement ring for protection
Research your options when it comes to insuring your ring. You can contact your agent for more details on the steps you should take.
9. Choose an officiant for the ceremony

8 months before your wedding day

 10. Select a photographer and videographer
  • Decide on a photography style – candid, classic, edgy?
  • Read client reviews.
  • Interview prospective photographers and view their work.
  • Compare photo packages.
  • Inquire about your rights to the photos, since many photographers own the rights to all wedding images.
  • Find out post-production details, such as how long it takes to get your photos, how many you’ll receive, and whether the photographer offers retouching options.
11. Decide on entertainment
When choosing between a band or DJ, consider the following:
  • Vibe – Music sets the tone, theme and ambiance of your wedding
  • Variety – Make sure the entertainment can play the mix of genres you desire
  • Budget – While a DJ generally costs less than a band, the price of a band often depends on the number of musicians
  • Space – Check with the venue about restrictions. For example, is there a limit to the number of musicians or pieces of equipment you can bring in?
12. Choose a caterer
Schedule a tasting of what you want to serve and find out exactly what’s included, such as plates, silverware, table linens, etc.
13. Plan attire for the bride, groom, bridesmaids, groomsmen, flower girl and ring bearer
Schedule fittings and keep track of dates. Don’t forget jewelry, bag, shoes, bridal veil and other accessories.
14. Reserve a block of hotel rooms for out-of-town guests
15. Register for gifts with at least three retailers
Print out a wedding registry checklist to avoid missing any essentials.
16. Look into coverage options for any new gifts you receive
Check your homeowners or renters policy to find out if new gifts are already covered. If not, look into different property insurance options that could insure your new items.

7-6 months before your wedding day

17. Design invitations
  • Choose text and colors that are legible.
  • Order at least 25 extra invitations in the event of re-sends.
18. Plan your honeymoon
Planning your honeymoon well in advance can help avoid any last minute problems and can save you money. It’s also a good idea to get travel insurance so you’re protected if an incident affects your trip.
19. Send save-the-date cards
20. Reserve things like portable restrooms and outdoor lighting if needed
21. Book a florist
22. Create a music playlist, including a list of no-play songs
23. Arrange transportation for guests
  • Book transportation for the wedding party, as well as for you if you plan to arrive separately.
  • Hire a shuttle or bus to take guests to and from the hotel.

5-4 months before your wedding day

24. Finalize the menu
25. Choose a wedding cake
Schedule a tasting with bakeries so you can try different types of cakes, ask questions and review the bakery’s portfolio.
26. Address wedding invitations
Consider hiring a calligrapher to make your invitations more elegant and consistent.

3 months before your wedding day

27. Map out the ceremony with your officiant
28. Choose wedding favors for your guests
29. Create a list of who will be toasting at the reception
Be sure to allot time for speeches in your day-of schedule.
30. Purchase bride and groom wedding bands

2 months before your wedding day

31. Confirm times with all vendors
Send your day-of schedule to vendors and confirm appointments for hair and makeup.
32. Buy gifts for your wedding party
33. Send invitations

1 month before your wedding day

34. Get your marriage license
35. Separate RSVPs as you receive them by “attending” and “not attending”
The RSVP date should be 2-3 three weeks before your wedding in order to give the caterer a head count and set your seating chart a week ahead of time.
36. Schedule the timing for all day-of activities, such as the cake cutting and the first dance
A wedding planner or coordinator can help.
37. Put together gift bags for out-of-town guests

Week of the wedding

38. Assign seating for the reception
Create a seating chart at least a week before the big day. A site like seatingarrangement.com can help with the task.
39. Confirm honeymoon details
40. Deliver gift bags to guests at the hotel
41. Put tips and final payments for vendors into separate envelopes
42. Pack for your honeymoon
Check out our tips for efficient packing, and our guide to following TSA carry-on rules so your honeymoon isn’t derailed at the airport.
43. Breathe and enjoy as all your planning comes together!

Friday, January 26, 2018

7 Ways to Teach Kids How to Save Money


Starting early can make a world of difference when it comes to teaching children to save and make sound financial decisions.
Luckily, there are simple ways to teach kids about money and help youngsters learn smart saving techniques. Here are some approaches to teaching children the valuable art of saving.

1. Teach kids about money with actual money 

In a world where anything can be purchased with the swipe of a card or typing of a password, the simple reality of cash can help teach the value of a dollar. That’s why using physical currency can be a smart way to teach kids about money. Counting coins and bills can also help preschoolers with hand-eye coordination and math skills.

2. Give an allowance

Giving children their own money is a good way to start teaching them how to save. Kindergarten is a great age to start a weekly or monthly allowance. A good rule of thumb is to pay $1 for every year of their age, so the incentive grows as they do. Make sure the allowance is based on completed chores, though. That way, kids understand that money is earned.

3. See the savings

Using a clear container as a bank can help give kids a sense of accomplishment watching the coins and dollars stack up. Make goals visible by marking a line on the side of the container as a target to reach. Not only does this teach children about saving, it makes reaching goals exciting and fun!

4. Teach children to allocate their savings

To introduce money management, as well as delayed gratification and charity, encourage your child to divide their money into three piles: savings, spending and sharing. You can do this online with the website Threejars.com, where kids can track their earned allowance and even earn interest on savings.

5. Set saving goals

Help your child develop savings targets to make sure savings isn’t an open-ended concept. The first goals should be reachable, fun and defined by both the parent and child. Sure, it may seem silly to save for a small toy, but the sense of achievement is worth it.

6. Teach kids about saving money in a bank account

As your child matures and has accumulated at least $100 in long-term savings, look into a bank savings account. Most major banks offer children’s savings accounts that can be opened online or at a local branch. A trip to the bank may be a new and fascinating experience for your child, inspiring a sense of maturity and financial responsibility. It’s also a great time to teach kids about other money concepts, like interest and risk.

7. Have conversations about saving

The best tool for money management is conversation. Parents should talk to their kids about money matters like budgeting and investing. Aim to mirror good money behaviors, but remember it’s also okay to admit to your own money mistakes.
Show your kids what smart money management is. Visit Nationwide Bank for information on banking, investing and more.

Monday, April 10, 2017

How to Buy Life Insurance: a Guide


Purchasing life insurance is often a good decision. It protects your family financially when the unthinkable happens. Peace of mind for the future of your family requires some research and taking a few steps to find the best life insurance policy for your needs.
So, how do you buy life insurance? We break down the ways to get life insurance below.

Getting life insurance from your employer

Many employers offer group life insurance as a company benefit, whether they pay the entire premium or subsidize it. In fact, group life insurance represented 43% of all U.S. life insurance policies in 2014, according to the American Council of Life Insurers.
There are several advantages to these policies. If the company pays all or most of the cost, that’s, of course, a monetary savings for employees. However, the amount purchased may not meet your ultimate needs. If the benefits equal one or two times your salary, that’s probably not enough to leave your family in a comfortable financial position should you unexpectedly pass. You may have the option to upgrade the policy to a higher amount by paying the difference, or you can use this policy as a secondary one, purchasing an individual policy elsewhere.
One huge upside to group life insurance is you don’t usually have to take a medical exam to get it. It is easier to obtain group life insurance in these situations than as an individual.
The downside to getting life insurance through the employer is the coverage usually ends when employment ends. If you leave your job, whether you’re laid off or proactively find a new one, your life insurance policy doesn’t come with you. You might be able to convert it to an individual policy, but the costs may be higher than one acquired on your own. While a new employer might also offer life insurance benefits, there may be a waiting period.

Getting life insurance independently

If you want to buy life insurance independently of your employer, you can go to a specific insurance carrier or an online broker that sells policies from different companies. If you know what kind of insurance you want, you can get quotes online or with a phone call.
The advantage to getting online or phone quotes is you can get pricing information quickly and then compare quotes. If you go that route, it’s helpful to have a strong insurance background because you won’t be getting as much guidance as you would through your personal insurance agent. You might be comparing policy options without understanding the differences.

Talk to an insurance agent

Calling or meeting with a personal insurance agent is another way to get life insurance. Some insurance companies offer discounts to customer who bundletheir policies, like having homeowner, auto and life insurance all with the same carrier.
The advantage to using personal insurance agents is they already understand your financial needs and they care about you as a long-term customer. They’ll spend the time to discuss the various life insurance types so you can find the best one for you. The disadvantage to using your personal agent is that they may be tied to only one insurance carrier, so they may not be able to offer you life insurance options from other companies.

What’s next?

Once you’ve chosen the policy you want and gotten a quote, you’ll apply for the insurance. That involves speaking with an insurance agent, even if you got your quote online. The agent will ask some questions and discuss the policy you chose. The agent will also send you paperwork to fill out and sign.
It’s likely that you’ll need a medical examination as the next step. The company will contact you to set up a time. The examiner will come to your home or office for some basic testing, such as determining your weight, getting a blood sample, perhaps an EKG, and listening to your heart.
This entire underwriting process can take a few weeks. Assuming everything checks out, the insurance company will send you the policy approval and ask for payment, if you haven’t already given a deposit. The premium might be different than in the original quote, depending on the results of your  medical exam and risk category.

Monday, February 6, 2017

Casa del Barco restaurant opening second location with rooftop tequileria in Short Pump Town Center

BY KARRI PEIFER Richmond Times-Dispatch


Casa del Barco, the Mexican restaurant that Richmond restaurant Kevin Healy opened on the Canal Walk in 2013, is planning a second location in Short Pump Town Center.

The restaurant will join its sister restaurant The Boathouse, which opened its third location in the mall in 2015. The new Casa del Barco will be in the former Tara Thai.
This location will be 8,400 square feet and include an "open-air rooftop tequileria" with a menu of 200 tequilas or mezcals. There will also be a private dining.
“We wanted to find the right fit for our second Casa del Barco location and when the opportunity to open at Short Pump Town Center was available, we knew we couldn’t pass it up,” Healy said.
The new Casa del Barco is expected to open this summer and will create 85 jobs, according to a news release. The restaurant will serve lunch, dinner and Sunday brunch.

The Boathouse restaurant group is also working on a The Boathouse restaurant location in Hopewell. That spot is slated to open in April or May.

Original Article

Saturday, January 7, 2017

Tips for a Safe Winter Road Trip


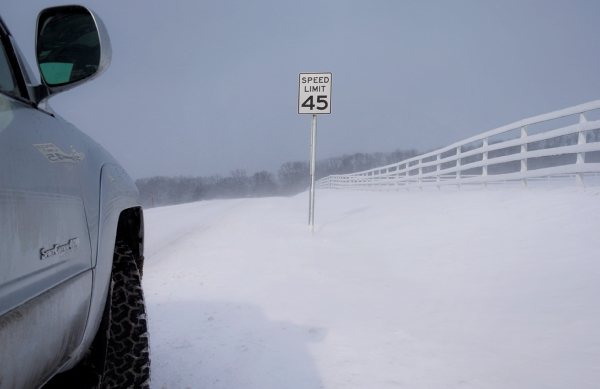
Winter can be a popular time for a road trip, with families visiting friends and relatives for the holidays or driving to the mountains for fun in the snow. It’s also the time of year when road conditions are typically at their worst, requiring extra care before loading up the car and heading out. With some careful planning and cautious driving, though, you can make it safely to your destination.
Cold temperatures and wintry conditions can be tough on a car. You want your vehicle to be in the best working condition possible, which can go a long way toward avoiding trouble on the road.
Start by taking your car in for regular maintenance and service, including changing the oil to a weight, or viscosity grade, best suited for cold weather. A good mechanic will check your belts and hoses and make sure everything is in good shape and free of leaks. Check on whether you have enough coolant as well, and that it’s made for low temperatures.
“One of the most common winter driving woes is underinflated tires,” says Greg Cohen, president & CEO of American Highway Users Alliance. “Before taking a trip, check your tires and make sure they are inflated to the amount described in the driver’s door jamb. Also, check the condition of your wipers, have a full tank of wiper fluid, and check your oil.”
Visibility is vital in wintry weather, so use washer fluid designed for freezing conditions. “Pack an extra jug of winter wiper fluid, a strong flashlight with fresh batteries, and an ice scraper and snow brush,” Cohen says. Avoid driving on icy, slushy, or snowy winter roads, if possible.
It’s advisable to check your battery and get it load-tested. Cold temperatures can sap a weak battery’s ability to start your engine, a predicament you want to avoid. Other items to bring include an emergency road kit with flares or triangle reflectors, jumper cables and a first-aid kit. “Make sure you have at least a half tank of fuel, a bag of road salt, a fully charged mobile phone, a warm coat, winter gloves and hat, and warm clothing in case of a breakdown,” says Cohen.
It’s important to be aware of weather forecasts along your route and to stay on top of weather changes and road closings that can happen suddenly. Learn the different kinds of weather advisories from the National Weather Service. A “winter storm watch” is issued 12 to 48 hours in advance of a storm’s arrival with potential for heavy snow or ice, while a “winter storm warning” means a storm is occurring, or about to occur in your area usually within 36 hours. A “blizzard warning” means winds of at least 35 mph with heavy snow forecast for a period of 3 hours or more.
Once you’re out on the road, “be prepared for changing road conditions along road sections and from one road to the next,” says Cohen. “Expect road conditions to vary depending on the amount of congestion, type of pavement, and frequently changing maintenance jurisdictions. Use caution and steer carefully through turns. Bridges and ramps freeze before roadways, so be sure to avoid sudden speed changes and lane changes.”
The concentration needed for driving in wintry conditions can be exhausting, so stay alert and take plenty of rest breaks.
If possible, avoid driving on roads until they’ve been plowed and de-iced. On roads that have yet to be cleared, slow down, turn off your cruise control, and avoid sudden braking or acceleration and unnecessary stops. If you suddenly feel your tires have lost their grip on the road, stay calm and gently steer in the direction you wish to go without over-correcting. Keep a light touch on the steering wheel; a white-knuckle grip can lead to overreaction and loss of control.
When bad weather strikes while you’re driving, head for a service station or truck stop at the first chance and wait it out. But if you suddenly find yourself stranded on the side of the road, stay calm, put on your hazard lights and call 911. After,  you should also contact your insurance provider, they can provide additional help such as Nationwide’s Roadside Assistance.
“If it is safe to do so, make sure your car is visible to others by carefully placing emergency flares and/or reflective triangles a safe distance behind your car,” says Cohen. “Return to the warmth and safety of your car, call for a tow truck, and stay in your car until help arrives. Remember, the safest thing you can do is to stay in your car, only exiting when absolutely necessary to keep the vehicle visible to other drivers.”
By planning ahead, taking precautions while driving, and following safety steps in the event of a breakdown, your winter road trip can be a trouble-free time on the way to your destination.

Check out the original article right here...