Showing posts with label best insurance companies. Show all posts

Wednesday, February 14, 2018

The Complete Wedding Planning Checklist: 43 To-Do’s Before Saying Your “I Do’s”


couple sitting together at a wedding


The congratulatory calls and engagement parties have waned. Now what? It’s time to get down to serious wedding planning. Fun? Yes! Overwhelming? Oh, yes. But don’t fret. We’ve compiled this pre-wedding timeline and wedding planning checklist for soon-to-be brides and grooms.

16-9 months before your wedding day

1. Create a file or binder to keep wedding information organized and together
  • Wedding planning sections should include the following:
    BudgetDate
    VenueGuests
    Wedding partyVendors
    AttireStyling
    CeremonyReception
    EntertainmentMenu
    Pre-wedding plans: rehearsal dinner, bachelor party, bridal shower etc.Post-wedding plans: honeymoon
2. Plan your budget. TheKnot.com’s budget allocation chart can help:
Reception48-50%
Attire8-10%
Flowers/Décor8-10%
Entertainment/Music8-10%
Photography/Video10-12%
Favors and Gifts2-3%
Ceremony2-3%
Stationary2-3%
Wedding Rings2-3%
Transportation2-3%
Miscellaneous8%
When planning your budget, it’s a good idea to avoid piling up bills that you’ll be paying back for years to come. Here are some wedding financing tips to help you avoid going into debt. 3. Set a date and reserve a venue for the ceremony and reception
3. Set a date and reserve a venue for the ceremony and reception
Research listings and compare features, cost, size, etc. Arrange visits and bring a list of questions to ask venue planners. Also, consider wedding insurance for protection in case of a cancellation or damage to the venue.
4. Create the guest list
  • Draft the list based on your budget and venue size.
  • Use Google Docs or similar resources to keep the list organized and easily editable.
  • Make sure guests’ names are on the RSVP card to avoid any confusion.
5. Choose your wedding party
6. Hire a wedding planner to help with details
7. Have the engagement ring appraised
You will most likely be able to have your ring appraised for free at the jewelry store where the ring was purchased. In the event your ring is lost or damaged, it’s a good idea to keep the appraisal and receipts in a safe place.
8. Insure the engagement ring for protection
Research your options when it comes to insuring your ring. You can contact your agent for more details on the steps you should take.
9. Choose an officiant for the ceremony

8 months before your wedding day

 10. Select a photographer and videographer
  • Decide on a photography style – candid, classic, edgy?
  • Read client reviews.
  • Interview prospective photographers and view their work.
  • Compare photo packages.
  • Inquire about your rights to the photos, since many photographers own the rights to all wedding images.
  • Find out post-production details, such as how long it takes to get your photos, how many you’ll receive, and whether the photographer offers retouching options.
11. Decide on entertainment
When choosing between a band or DJ, consider the following:
  • Vibe – Music sets the tone, theme and ambiance of your wedding
  • Variety – Make sure the entertainment can play the mix of genres you desire
  • Budget – While a DJ generally costs less than a band, the price of a band often depends on the number of musicians
  • Space – Check with the venue about restrictions. For example, is there a limit to the number of musicians or pieces of equipment you can bring in?
12. Choose a caterer
Schedule a tasting of what you want to serve and find out exactly what’s included, such as plates, silverware, table linens, etc.
13. Plan attire for the bride, groom, bridesmaids, groomsmen, flower girl and ring bearer
Schedule fittings and keep track of dates. Don’t forget jewelry, bag, shoes, bridal veil and other accessories.
14. Reserve a block of hotel rooms for out-of-town guests
15. Register for gifts with at least three retailers
Print out a wedding registry checklist to avoid missing any essentials.
16. Look into coverage options for any new gifts you receive
Check your homeowners or renters policy to find out if new gifts are already covered. If not, look into different property insurance options that could insure your new items.

7-6 months before your wedding day

17. Design invitations
  • Choose text and colors that are legible.
  • Order at least 25 extra invitations in the event of re-sends.
18. Plan your honeymoon
Planning your honeymoon well in advance can help avoid any last minute problems and can save you money. It’s also a good idea to get travel insurance so you’re protected if an incident affects your trip.
19. Send save-the-date cards
20. Reserve things like portable restrooms and outdoor lighting if needed
21. Book a florist
22. Create a music playlist, including a list of no-play songs
23. Arrange transportation for guests
  • Book transportation for the wedding party, as well as for you if you plan to arrive separately.
  • Hire a shuttle or bus to take guests to and from the hotel.

5-4 months before your wedding day

24. Finalize the menu
25. Choose a wedding cake
Schedule a tasting with bakeries so you can try different types of cakes, ask questions and review the bakery’s portfolio.
26. Address wedding invitations
Consider hiring a calligrapher to make your invitations more elegant and consistent.

3 months before your wedding day

27. Map out the ceremony with your officiant
28. Choose wedding favors for your guests
29. Create a list of who will be toasting at the reception
Be sure to allot time for speeches in your day-of schedule.
30. Purchase bride and groom wedding bands

2 months before your wedding day

31. Confirm times with all vendors
Send your day-of schedule to vendors and confirm appointments for hair and makeup.
32. Buy gifts for your wedding party
33. Send invitations

1 month before your wedding day

34. Get your marriage license
35. Separate RSVPs as you receive them by “attending” and “not attending”
The RSVP date should be 2-3 three weeks before your wedding in order to give the caterer a head count and set your seating chart a week ahead of time.
36. Schedule the timing for all day-of activities, such as the cake cutting and the first dance
A wedding planner or coordinator can help.
37. Put together gift bags for out-of-town guests

Week of the wedding

38. Assign seating for the reception
Create a seating chart at least a week before the big day. A site like seatingarrangement.com can help with the task.
39. Confirm honeymoon details
40. Deliver gift bags to guests at the hotel
41. Put tips and final payments for vendors into separate envelopes
42. Pack for your honeymoon
Check out our tips for efficient packing, and our guide to following TSA carry-on rules so your honeymoon isn’t derailed at the airport.
43. Breathe and enjoy as all your planning comes together!

Friday, February 9, 2018

10 Medicine Cabinet Essentials

well-stocked medicine cabinet

When it comes to first aid in the home, be prepared with a well-stocked medicine cabinet. If you need to treat an illness or injury, you will have all the basics on hand to help yourself or others.
Before you head to the drugstore, take an inventory of your medicine cabinet and what’s currently on your shelves. This is a good opportunity to clear your medicine cabinet of old prescriptions and expired products. Make this a habit and try to do this every three months. Find a local center near you that can properly dispose of old medication. Some grocery stores or community centers offer this service annually. By doing this, you won’t have to worry about how long that bottle of pink liquid has been sitting on your shelf the next time you have a sudden stomach ache.
Remember: Always follow dosage instructions as indicated on medication packaging.

Medications and first aid supplies to have on hand at all times

The following medicine cabinet supplies can treat a range of illnesses and minor injuries, from allergies and stomach aches to cut, bruises, aches and pains.
1. Emergency instructions
Tape a list of important phone numbers (doctors, Poison Control), medication instructions and allergy alerts inside the cabinet door.

2. Acetaminophen and an NSAID

Acetaminophen is a pain reliever and fever reducer. Non-steroidal anti-inflammatory drugs (NSAIDs) can reduce inflammation related to conditions like backaches and toothaches. Be aware of NSAID sensitivity in your family, especially in young children.

3. Aspirin

Aspirin works as a pain reliever for adults, but it’s also important to have on hand in case of emergencies. According to the American Heart Association, taking aspirin also helps during a heart attack. In fact, people having a heart attack are often given an aspirin by emergency medical services. However, it’s wise to be aware of aspirin sensitivity in your family, and it should never be given to children under 18.

4. Antihistamine

Antihistamines treat hives, itching and allergic reactions from a wide range of causes. Stock both oral antihistamines (the liquid or pill form that may be helpful during a serious allergic reaction) and hydrocortisone cream.

5. Decongestant, cough suppressant and flu relief medicine

You won’t want to leave home to go to the drugstore when you’re feeling lousy, so keep cold and flu relief medication on hand.

6. Antacids

If you are suffering from heartburn, these are your best bet for quick relief.

7. Antibiotic ointment

Apply this after you’ve washed cuts and scrapes with warm water and soap, then cover the wound with clean bandages.

8. Bandages

Stock up on adhesive bandages of all sizes, plus plenty of gauze and sterile tape.

9. Thermometer

Feeling someone’s forehead may be a good first step, but a thermometer is necessary for an accurate temperature reading.

10. Heat and ice packs

Keep several of these on hand, as they can provide relief for everything from headaches and sprains to injuries and sore muscles.
Staying healthy and safe is everyone’s concern. But if someone gets injured on your property, you’ll need more protection than what’s available in your emergency medicine cabinet. Make sure you’re covered with personal umbrella liabilitycoverage from Nationwide, which may help protect you beyond your homeowners insurance coverage limits.

Wednesday, February 7, 2018

How Much Does Pet Insurance Cost?

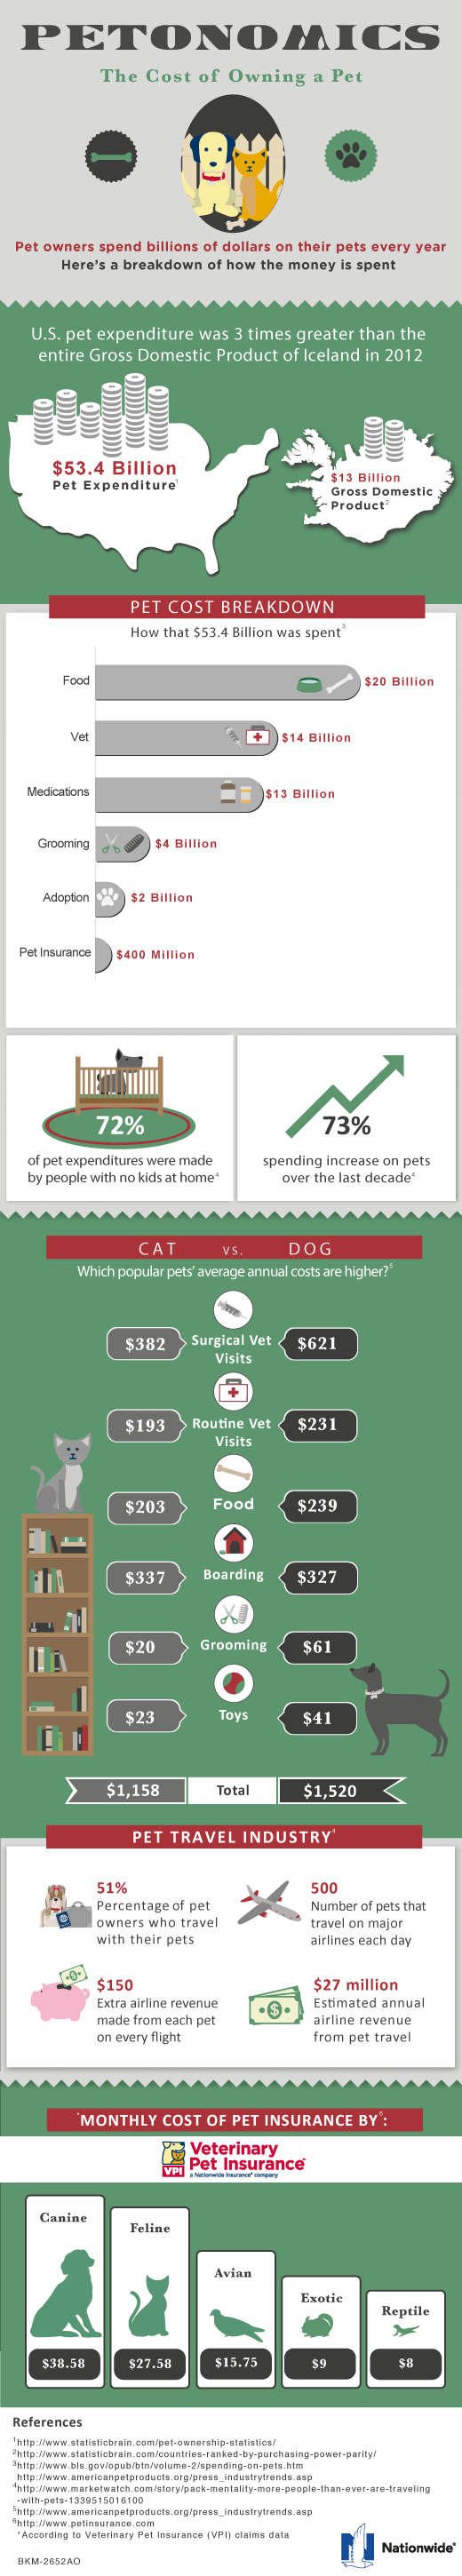
The average dog owner spends $852 annually on routine and surgical visits to the vet. Insuring your pet can help ease the financial burden. The cost of pet insurance is not only affordable, it can also help you save on pet care through reimbursements. With Veterinary Pet Insurance (VPI), monthly insurance plans might be less than you think:

Average monthly cost of pet insurance

  • Dog Insurance Cost: $38.58
  • Cat Insurance Cost: $27.58
  • Bird Insurance Cost: $ 15.75
  • Exotic Pet Insurance Cost: $9
  • Reptile Insurance Cost: $8
Compared to the monthly price of your pet’s food, the cost of pet insurance is a small price to pay for your animal’s protection.
How Much Does Pet Insurance Cost? [Infographic]

Monday, February 5, 2018

The Benefits of Minimalist Living

Living a minimalist lifestyle with smaller rooms
Accumulating things is just part of life. There are the items we need, and then there are those we don’t really need — but how much is too much? At a certain point, you may feel overwhelmed or crowded by all of your stuff. Your things may cease to have meaning, or worse, you may not be able to locate important items.
If this sounds right, it might be time to adopt a minimalist lifestyle. From a practical standpoint, relinquishing objects can help you de-clutter your living space. It also may have symbolic value, signaling a change in your perspective and priorities in life.

1. Create a minimalist living plan

You’ll have to prioritize the objects you can’t live without and those that are less important. Every room in the house can accumulate clutter. Don’t ignore any opportunity. Remember that you want fewer items.
One great way to get started with a minimalist lifestyle is to formulate a plan to systematically go through your things and determine what you want to keep. It can feel overwhelming to think you need to tackle everything in one day – and you don’t need to. Instead, break each part of the process into steps.
One idea is to set a goal of going through one room a day – or a weekend for larger rooms with more items, like your kitchen. Or, if you have a bunch of boxes to go through, sort one every evening after you get home from work. It can also help to set up a staging area somewhere else in your home; seeing the items outside their “natural habitat” makes it easier to think about their utility. However you declutter, choose the pace that works for you, and remember it’s not a race. It took time to accumulate things, and it can take some time to declutter, too.

2. Artwork and decorative objects

Artwork and ornamental objects can create a richer environment, but they’re not a necessity and can easily clutter a room. They may serve as a good starting point in your minimalist efforts. Keep only what has nostalgic value or that’s meaningful and attractive, and sell or give away the rest. If an art piece is valuable enough, consider donating it to charity.

3. Living with less furniture

Many houses have extra furniture on hand, which can overcrowd the space. Think about taking out pieces, starting with the ones that you simply don’t like anymore or that aren’t essential for your convenience or comfort. If you don’t use it frequently or have a need for it, don’t hesitate to get rid of it. Remember that some charitable services and thrift stores will pick up bulky items you want to donate.

4. Kitchen equipment and utensils

Culinary-minded households acquire kitchen gadgets and utensils quickly. You might like the aesthetics of certain items or want to purchase the latest devices. But too many small appliances and tools, like food processors and blenders, can monopolize your counter and cabinet space. So can those utensils you have doubles or even triples of — there are only so many spatulas, serving spoons or pots that you need.
Look for kitchen items you’re not using frequently or that you have multiples of. If you do an effective job of streamlining your kitchen, you’ll find that this room is easier and more enjoyable to use. This is also a helpful way to prepare for a remodel.

5. Clearing out clothing

It’s not unusual to see bedroom closets and dressers overflowing with clothes. Many of us own extra clothing, and many of us also don’t wear a good portion of our wardrobes. If you’re overstocked, pinpoint the items that you wear most frequently and donate the rest.
With these helpful ideas in mind, it’s easier to begin the de-cluttering process on your path to a more minimalist lifestyle. Whether you’re preparing for a move, cleaning the kids’ rooms after they’ve left for college or looking into adopting minimalist living, a decluttered living space provides contentment and relaxation.
Looking to enjoy even more peace of mind at home? Nationwide’s homeowners insurance coverage can help protect your important belongings, regardless of how minimalist your lifestyle is.

Monday, January 29, 2018

Nationwide Recognized for Providing Outstanding Retirement Plan Service

DALBAR, the nation’s leading financial services market research firm, has once again honored Nationwide for its outstanding service to retirement plans. This year, Nationwide earned three separate DALBAR awards recognizing the level of service being provided to its retirement plan partners, plan sponsors and participants. The awards earned are:
  • 2017 Plan Participant Service Award for contact center support to plan participants in both public and private sector plans
  • 2017 Recognition for Excellence for telephone support and relationship management through the New Plan Implementation and Conversionsprocesses
  • 2017 Recognition for Excellence for email support and relationship management by the Client Services Team to plan sponsors, third-party administrators and financial advisors
2017 marked the fourth straight year that Nationwide has earned both the Plan Participant Service Award for contact center support and the Recognition for Excellence for email support to plan sponsors and TPAs. This is the third consecutive year that Nationwide has been recognized for telephone support and relationship management for new plan implementation and conversions.
“Nationwide’s focus on the customer experience extends across the life cycle of its retirement plans, from the initial implementation through disbursement,” said Brendan Yeager, DALBAR director.  “Nationwide is committed to providing an award-winning experience to all of its stakeholders, from the financial advisor and third-party administrator to the plan sponsor and, of course, individual participant. The company excels at both transactional interactions through its contact center and at building trust-based relationships with plan sponsors and business partners.”
Wendy Shaw, Nationwide’s vice president of retirement plan operations, said the awards demonstrate Nationwide’s commitment to providing a superior standard of care to retirement plan customers, and its ongoing investments in its people and technology.
“We’ve worked hard to build a culture that’s committed to excellence and continuous improvement,” said Shaw. “Our commitment extends from the plan sponsor or third-party administrator all the way to individual plan participants. It starts from the time a retirement plan comes to Nationwide and carries through to each and every plan sponsor and participant interaction – from their first payroll contribution all the way through retirement. These awards are clear evidence that we are delivering on that promise, and we’re extremely proud of our service leaders and associates who consistently deliver an outstanding experience to our retirement plan clients.”
The recognition of excellence is only awarded to firms that exceed strict standards for communication. The service award is based on systematic testing of customer service throughout the year based on thousands of tests measuring how financial companies respond to the service needs of their customers.
Learn more about how you can begin working with Nationwide’s award-winning retirement planning services to help you prepare for the future.

Wednesday, January 24, 2018

How to Negotiate Your Rent

woman negotiating her rent with landlord

Whether you’re apartment hunting and the perfect place is slightly out of your price range, or your landlord is raising the rent on your current apartment, you have the option to try and negotiate your rent. It sounds intimidating, but with a little strategy, you just might win over the landlord. Here are some ways you can go about negotiating your rent price:

Ask the landlord if rent price is open to discussion

Politely ask if the landlord is willing to discuss rent prices and when a good time to talk would be. If you’re negotiating price for a new place, it’s important to know who you are talking to. A large property company is less likely to negotiate terms, while an independent landlord has more leeway to change prices.
If you’re facing a rent increase, start the conversation at least a month before your lease ends so your landlord has enough time to consider your offer or, if need be, you have time to make other plans.

Highlight your strengths as a tenant

If you’re looking for a new place, you can show you’re financially stable by offering the landlord a few concessions, such as paying a few months of rent in advance or signing on for a longer lease which saves the landlord money in turnover.
In the case of a rent increase, you should remind the landlord what a reliable, responsible tenant you’ve been. If you’ve always paid your rent on time, are courteous to other tenants and have kept the property in good shape, make sure your landlord knows it. It can help prove your worthiness and give them an incentive to keep your current rent.

Inquire about extending the lease

Showing that you plan to stay in your apartment for a substantial length of time can demonstrate that you’re a stable investment. If the lease is annual, offer to extend it to 18-24 months in exchange for keeping your current rent. If the landlord knows he or she won’t have to take a risk with a new tenant, this could be a good compromise.

Offer to end the lease in the summer

Landlords know the summer is usually an easier time to find tenants. Since most people have more flexible schedules then, such as recently graduated college students looking for first apartments, there are simply more people looking for rental spaces. Offering to end your lease in the summer can be an attractive option for a landlord, and they might be willing to shave prices in exchange for the convenient end date.

Research the property’s value

Consider if the is rent beyond the actual worth of the prevailing market. Research rent rates by talking to other landlords or neighbors in the area. Knowing average property prices and frequency of rent hikes in the neighborhood may give you leverage.

Be open to compromise

Unless you’re simply unwilling or unable to afford the rent rate, suggest a compromise amount that you can afford. For instance, if the rent is $100 higher than you’d like, offer to pay $50 instead. Back up your offer by mentioning your research findings and focusing on your stability as a tenant.

Negotiate in person, follow up in writing

Try to talk to the landlord in person as face to face negotiation is usually best. Remain calm, polite and professional during the discussion – never rude or defensive. Follow up the discussion within 24 hours with a brief email thanking them for the meeting and reiterating your “ask.”

Have a backup plan

If you’re looking for a new place, you should have more than one apartment, house or condo on your radar. Banking on a landlord decreasing rent prices can be risky, especially if you have a set date you need to move out of your old place.
If you’re facing a rent increase, you have to decide if you’d be willing to pay the higher rate just in case negotiations don’t go as planned. If you are definitely unwilling or unable to accept the new rate, it’s a good idea to start researching new apartments. If you decide to stay and pay more each month, you can request property upgrades to make the increase more palatable, such as repainting the walls or updating the landscaping.

Rent increases aren’t the only unexpected thing that can happen to renters. Find out how Nationwide renters insurance can protect you against theft, damage to personal belongings, and more.

Thursday, August 10, 2017

7 Summer Energy-Saving Tips to Lower Your Electric Bill

summer energy-saving tips
Figuring out how to lower electric bills in the summer can be difficult, especially when temperatures are at their hottest. Luckily, there are some steps you can take to save on your electric bill during the summer months. Try these 7 summer energy-saving tips so you can focus less on your electric bill and more on the pleasures of summer.

How to lower electric bills in the summer

1. Be smart about peak-time summer utility rates.

Plan to run your washer, dryer and dishwasher before 11 a.m. or after 7 p.m. to avoid peak usage times and potentially higher rates. Utility companies often raise gas and electricity rates during the hottest time of the day, according to Energy Upgrade California. You can still load the dishwasher after meals, but waiting a bit to run it can help lower summer electric bills.

2. Look for the Energy Star symbol.

Planning to replace your washer, dryer or refrigerator? Shop with energy savings in mind. The U.S. government’s Energy Star program certifies products that meet strict energy-saving specifications. According to Energystar.gov, washers built before 2003 are significantly less efficient than newer models. Energy Star washing machines use about 25% less energy and 40% less water compared with regular washers. Similar money and energy savings can be found in newer dryers, refrigerators and other appliances that are Energy Star-certified.

3. Think outside the oven.

Running your oven on hot days makes your air conditioner run more to keep the house cool. Firing up the backyard grill for a barbecue instead can help you save on your electric bills in the summer.

4. Make cooling off a breeze.

Install ceiling fans, which can help everyone in the room feel cooler without the need to run the A/C as much – or at all. While the fans don’t actually lower the temperature in the room, they create a wind-chill effect and make you feel cooler by accelerating the evaporation of perspiration on the skin. Another summer energy-saving tip: Ceiling fans are of no use when no one is in the room, so turn them off when you leave.

5. Insulate your home.

Heating and cooling account for 50% to 70% of the energy used in the average American home, according to the U.S. Department of Energy (DOE). Reducing the energy spent on cooling by improving insulation is a great way to lower your summer electric bills. Newer homes generally are better insulated than older, unimproved homes because building energy codes have become progressively stricter over the years, says the DOE. If you have an older home, consider adding better insulation. Unless your newer home was constructed with special attention to energy efficiency, your utility bills will still probably benefit from improving your home’s insulation.

6. Check for air conditioner efficiency.

The DOE recommends having a professional check and clean your air conditioner (and your heater) once a year. If the unit is more than 15 years old, you may want to consider replacing it with a newer, more energy-efficient unit. A new system can greatly reduce your energy costs, says the DOE, especially if the existing equipment is in poor condition. On your current system, check your ductwork for dirt streaks, especially near seams. These indicate air leaks, and they should be sealed with a duct mastic sealant. Keep yard debris away from the outside compressor of your air-conditioning unit and keep nearby bushes trimmed.

7. Create your own shade.

Keep draperies and blinds closed on the sunny side of the house. Adding awnings can help, too. Looking for a longer-term solution that will add to the beauty of your property? Plant trees. “This Old House” recommends particular trees for fast-growing (1½ to 2 feet per year) shade options.
Your home isn’t the only place that can benefit from being cooled down in the summer. Once you finish using these summer energy-saving tips for your home, check out some tips for keeping your car cool in the summer.

Thursday, June 22, 2017

Pet Safe Summer: 3 Ways to Beat the Heat

heat stroke in dogs
Do you know how to keep your pet safe when the weather heats up? Like most people, you’re likely careful to never leave pets in vehicles when it’s hot outside. But there’s more to know when it comes to keeping pets cool, comfortable, and out of danger.
Dogs are generally at highest risk. When it’s hot, cats prefer to chill. Your dog, on the other hand, will try to go for a run or play fetch no matter the temperature. That means you must avoid hazardous situations and know what to do if your pet overheats. Some tips:
  • Keep the most at-risk pets inside and keep the air conditioning on for them. Older pets as well as kittens or puppies don’t handle weather extremes as well as healthy adult pets. In addition, dogs or cats of breeds known as “brachycephalic” – short-nosed pets such as bulldogs, pugs or Persian cats – have a greater difficulty keeping themselves from overheating. These high-risk pets should be kept inside where it’s cool, and any outings should be short – potty runs only.
  • Exercise your dog during cooler parts of the day. While short-nosed pets should be kept inside where it’s cool, other pets can enjoy supervised outdoor time early mornings or late in the day. Walks are good for both dogs and people, and you don’t have to skip them, just time them better. One rule of thumb: Put your hand on the sidewalk, and if it’s too hot to leave it there, it’s too hot for your pet’s paws.
  • Know the signs of overheating – and what to do if a pet gets too hot. Just as important as keeping pets out of heat danger is knowing what to do if a pet overheats. The signs in dogs – the most likely victims — are rapid, even frantic panting, very red gums, and a glassy look to their eyes. An overheated dog is in a life-threatening situation: Apply cool water – not icy cold, and not ice – to the groin area and get your pet to your veterinarian or an emergency veterinary hospital right away.
Whatever your summer activities, make sure there’s plenty of cool, fresh water available for your pets. When you’re out and about, take water with you and don’t let pets drink from pools, standing water or oceans. There are handy devices you can buy from pet product retailers to make it easy to bring water along. Products that have flip-down cups or nozzles mean you don’t have to carry a bowl with you.
Was the warning on leaving pets in vehicles is a new one for you? If so, you need to know this is a dangerous practice even on days that are merely warm, not hot. Even with the windows of your car cracked open, the temperature inside can build to a deadly level within minutes. If you’ll have to park your car for any length of time, leave your pet at home.
It doesn’t take much to keep your pets safe in the summer. Knowing how to protect your pet will allow you both to enjoy the warm summer days. In addition, the right pet insurance coverage can help you in the event of the unexpected.
To help keep your pet out of harm’s way, make sure you know these 20 common foods that can be dangerous for dogs and cats.

Monday, April 10, 2017

How to Buy Life Insurance: a Guide


Purchasing life insurance is often a good decision. It protects your family financially when the unthinkable happens. Peace of mind for the future of your family requires some research and taking a few steps to find the best life insurance policy for your needs.
So, how do you buy life insurance? We break down the ways to get life insurance below.

Getting life insurance from your employer

Many employers offer group life insurance as a company benefit, whether they pay the entire premium or subsidize it. In fact, group life insurance represented 43% of all U.S. life insurance policies in 2014, according to the American Council of Life Insurers.
There are several advantages to these policies. If the company pays all or most of the cost, that’s, of course, a monetary savings for employees. However, the amount purchased may not meet your ultimate needs. If the benefits equal one or two times your salary, that’s probably not enough to leave your family in a comfortable financial position should you unexpectedly pass. You may have the option to upgrade the policy to a higher amount by paying the difference, or you can use this policy as a secondary one, purchasing an individual policy elsewhere.
One huge upside to group life insurance is you don’t usually have to take a medical exam to get it. It is easier to obtain group life insurance in these situations than as an individual.
The downside to getting life insurance through the employer is the coverage usually ends when employment ends. If you leave your job, whether you’re laid off or proactively find a new one, your life insurance policy doesn’t come with you. You might be able to convert it to an individual policy, but the costs may be higher than one acquired on your own. While a new employer might also offer life insurance benefits, there may be a waiting period.

Getting life insurance independently

If you want to buy life insurance independently of your employer, you can go to a specific insurance carrier or an online broker that sells policies from different companies. If you know what kind of insurance you want, you can get quotes online or with a phone call.
The advantage to getting online or phone quotes is you can get pricing information quickly and then compare quotes. If you go that route, it’s helpful to have a strong insurance background because you won’t be getting as much guidance as you would through your personal insurance agent. You might be comparing policy options without understanding the differences.

Talk to an insurance agent

Calling or meeting with a personal insurance agent is another way to get life insurance. Some insurance companies offer discounts to customer who bundletheir policies, like having homeowner, auto and life insurance all with the same carrier.
The advantage to using personal insurance agents is they already understand your financial needs and they care about you as a long-term customer. They’ll spend the time to discuss the various life insurance types so you can find the best one for you. The disadvantage to using your personal agent is that they may be tied to only one insurance carrier, so they may not be able to offer you life insurance options from other companies.

What’s next?

Once you’ve chosen the policy you want and gotten a quote, you’ll apply for the insurance. That involves speaking with an insurance agent, even if you got your quote online. The agent will ask some questions and discuss the policy you chose. The agent will also send you paperwork to fill out and sign.
It’s likely that you’ll need a medical examination as the next step. The company will contact you to set up a time. The examiner will come to your home or office for some basic testing, such as determining your weight, getting a blood sample, perhaps an EKG, and listening to your heart.
This entire underwriting process can take a few weeks. Assuming everything checks out, the insurance company will send you the policy approval and ask for payment, if you haven’t already given a deposit. The premium might be different than in the original quote, depending on the results of your  medical exam and risk category.

Wednesday, February 22, 2017

What Kind of Car Is Best for Empty Nesters?


Once the kids fly the coop, it’s a time of change for parents. For many it can be a time to do things they’ve dreamed about doing – traveling or resuming a sport or hobby they’d set aside.

While some might dream about what they’ll do, others dream about what they’ll drive. A family car, SUV or mini-van might have been essential while the kids were still living at home, but parents find they can begin looking at smaller, more performance-based cars now. According to Bankrate.com, choosing a car as an empty nester can be very different from shopping for a family cruiser.

One of the greatest changes for the empty nester is that this is, quite likely, the first time in years that you’ve been able to think about buying a car specifically for your needs.

It’s no longer about how much sports equipment you’ll need to haul around or how many kids are going to pile in for a family vacation. It’s going to mean asking yourself an entirely different set of questions as you set out to buy.

Are we there yet?

For some, the idea of buying a car you want – instead of focusing purely on necessity and practicality – takes some getting used to. But the fact is, your living space isn’t the only thing you can look at downsizing once your children strike out on their own. This might be the time you start seriously looking at that sporty two-seater you’ve coveted since the moment you installed a child safety seat in your minivan.

Or you may have fewer day-to-day expenses, this could be the time you consider a luxury car. If it’s been a while since you’ve shopped for a car that didn’t have to include kid-friendly amenities, you might be surprised to find just how all-encompassing the luxury market is.

Where to begin

With so many options available to you, just defining what you want is a good start. Remember that what you want and what you need may be two different things; you might have to put some thought into both of those areas before coming up with your final answer.

Tim Shults, president of the Shults Auto Group in Jamestown, N.Y., says evaluating your needs, post-children, can be very different. In Newswheel.com, he wrote that some factors for empty nesters to consider are:

Technology: It’s a different world out there, particularly if you haven’t looked at new cars for a couple of years. Read up on the available technology and make sure you’re not buying more than you’re going to use. “GPS in your infotainment system would be incredibly helpful when you get lost, but you might not want to load up on all the latest tech that could distract you,” says Shults. Do your research ahead of time so you know what you do (and don’t) want.

Safety: Car safety features seem to be improving every day, and that’s reflected in the drop in the number of deaths caused by car accidents as technology improves. Sensors can help notify you when you’re out of your lane or have another car beside you; they can also help you back up and parallel park. “Take advantage of the sensors and cameras offered nowadays,” Shults advises. “Collision avoidance can save your life.”

Visibility: Making sure you have plenty of visibility is key in shopping for a new car, and with so many more options available to you it’s important to make sure you can see what’s around you. Take your time and test drive different models to see what feels best for you. Better visibility equals safer travels.

There’s no one-size-fits-all answer for empty nesters when it comes to buying a car. Some may want to buy a restored version of the car they longed for when they were teens and couldn’t afford; others may want the latest and greatest. Whichever route works for you, make sure you do your homework.

As your car needs change, your car insurance needs change too. Make sure you’ve got the right protection on the road and, most importantly, remember to enjoy the ride.

Originally Posted by Nationwide

Wednesday, December 21, 2016

How Much Should You Spend on an Engagement Ring?


There can be many factors that influence how much someone spends on an engagement ring. Though traditional standards suggest spending two to three months’ salary on a ring, many couples are now challenging the old rules and taking more personalized approaches.
A recent study estimates the average price of an engagement ring is $5,855. Still, there are no set rules. How much you should spend on an engagement ring will largely be dictated by your financial situation and what kind of ring your partner wants.
If you find yourself part of the average that can afford a $6,000 ring, then you will likely be looking for rings that meet certain standards of quality when it comes to the cut, color, clarity and carat weight, often referred to as the 4Cs grading system. At this price point, you will also be looking at a ring that has a carat weight of about 0.9 carats, the average carat weight for a purchased engagement ring in 2015.
Engagement rings with higher diamond grades usually have a greater carat weight and they are flawless. These rings have a tendency to be of rare quality and more expensive. In fact, rings of this quality can be the most expensive engagement rings you can buy, selling for between $500,000 and $8 million dollars.
Staying within your budget and purchasing something that can be treasured for years to come can be tricky, but there are different strategies available to you. Jewelry specialists often recommend buying a ring that’s just under the pricing plateau that’s higher than you want to go. So instead of a full carat ring, which sells at a premium rate, buy a 0.9 carat ring. These types of non-standard weights can reduce the cost of a ring significantly and with little noticeable difference in appearance.
Finally, if you are looking for something inexpensive but still stylish, a cubic zirconia engagement ring is a good option. For many it can be hard to distinguish between fake and real diamonds, and the difference in price is significant.
How much you spend on an engagement ring, whether it’s in a store or from an online retailer, will obviously be based on your personal financial situation. But with so many classes of rings out there, it’s possible to find something that you and your beloved really like that suits your budget, too.
Buying an engagement ring is the first of many decisions you’ll make when planning a wedding. Make sure to protect your special day with wedding insurance, which provides liability coverage and helps protect you from financial loss if you have to cancel or reschedule.